[🇧🇩] Banking System in Bangladesh

[🇧🇩] Banking System in Bangladesh
437
19K
More threads by Saif

G Bangladesh Defense

Private-bank seniors being hired to fill public banks' MD posts

Govt move meant to better manage banking operations, public banks' aspirants fear career blockage


1792626217487.webp


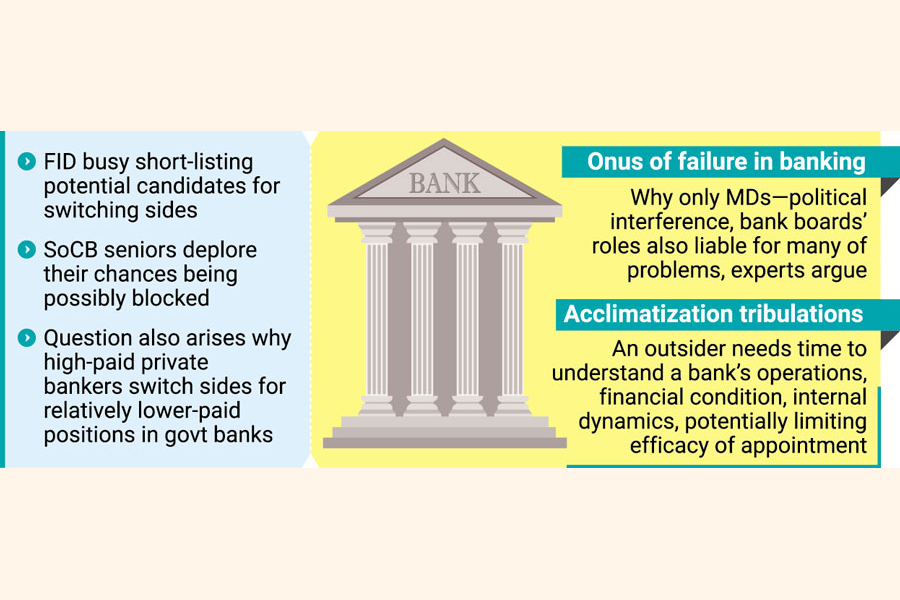
A plan is under active consideration of the government to appoint private commercial banks' senior executives as managing directors in state-owned commercial banks in a management reshuffle.

Meanwhile, the top executive posts in some public banks lay vacant following marching orders for the incumbents, ostensibly as the banks facing various problems.

The move comes after the Ministry of Finance opened the scope for appointing executives from outside the state-owned banks under a recently issued policy, sources have said.

According to the sources, the financial institutions division (FID) under the ministry of finance is busy making a list of potential candidates to be placed to the special committee led by the finance minister for final approval.

Contacted, FID additional secretary for the Central and Commercial Banks Wing Md. Azimuddin Biswas said the government can appoint anyone from existing pool of executives to state-owned banks, such as retired bankers or executives from the private-sector banks.

"There is no bar or restriction that senior executives from privately-operated banks cannot be appointed," he said, adding that a high-powered special committee led by the finance minister will finalise the names before sending it to the central bank for its clearance.

The government reportedly believes that bringing in executives from the private sector could improve corporate governance in state-owned banks and help reduce irregularities and corruption to bring back vibrancy in banking operations.

However, the possible appointments have triggered dissatisfaction among employees at different levels of state banks, who fear that such move could effectively block the career progression of deputy managing directors (DMDs) and other senior officials who have spent years working in the state-owned banking sector and traditionally aspire to become MD.

Bankers, speaking on condition of anonymity, have argued that some private-sector bank executives had failed to prevent their institutions from falling into serious financial distress.

Several private banks are currently undergoing merger processes amid mounting problems in the banking sector, they have pointed out.

A senior executive of a private bank, on condition of not being quoted by name, raised the question why executives drawing significantly higher salaries in private banks would be interested in taking relatively lower-paid positions at state-owned banks.

He said employees had legitimate expectations of reaching the top position after serving their institutions for many years.

"We have served the banks for years. Naturally, we expect to become managing director before retirement. But that opportunity is now being taken away," said one public-sector banker.

Another executive who spent more than 25 years in public banks said that irregularities and corruption in state-owned banks could not be attributed solely to managing directors as political interference and the role of bank boards were also responsible for many of the problems.

"Such appointments could create disorder within state-owned banks. Officials may not readily accept an MD coming from outside. That could ultimately hurt the bank," he told the FE.

He added that an outsider would also need considerable time to understand the bank's operations, financial condition and internal dynamics, potentially limiting the effectiveness of the appointment.

The government recently removed the managing directors of Sonali Bank, Janata Bank and Rupali Bank. Earlier, it had cancelled the remaining terms of the managing directors of BASIC Bank and Agrani Bank.

But the government did not publicly clarify whether the removals were made on political considerations or based on performance assessments.​
 

Learning nothing from past mistakes in banking


1792797234424.webp

A bank teller is counting notes at a bank branch in Dhaka — FE File Photo

The distress in the banking sector is hardly news to anyone following the economy. Nor did it arise overnight. Deliberate policy decisions and the organised plundering of banks during the latter half of the Awami League's 15 years misrule have created and compounded this banking crisis. The situation became so dire that five banks had to be merged into a single entity called Sammilito Islami Bank after massive loan defaults wiped out their share value. The alternative was simply to shut them down. Even this rescue has yielded little improvement as Sammilito Islami Bank continues to struggle. Of the remaining 56 banks, 22 to 23 remain burdened by heavy losses and capital shortfalls still today.

Just as banks are still absorbing the costs of those earlier policy missteps, the government is considering changes to the Bank Company Act that could allow powerful business families and their allies to keep their grip on banks. Rules designed to curb family control and limit directors' tenure are being relaxed, while provisions that hold directors accountable for loans taken by companies linked to them may also be weakened. This gives the impression that the authorities have learnt nothing from past mistakes and their devastating consequences.

Much of the damage inflicted on the banking sector stemmed from the very problem that the proposed changes risk perpetuating which is control over bank boards. Banks operate largely with money that belongs to other people, and their directors decide how the savings of ordinary citizens are to be used. When a family or a close circle of associates dominates the boardroom, distinction between a bank and family business can disappear. Lending decisions then serve the interests of the directors and their businesses rather than the long-term health of the bank. Depositors may believe their savings are entrusted to regulated financial institutions, but in effect, those in control may empty out the banks as though the money belongs to them.

The country paid a heavy price for such arrangement under the Awami League regime. Powerful business groups like S Alam, Beximco, Premier and Sikder reportedly took control of several banks by putting spouses, children, in-laws and other close associates on their boards. The rules that allowed this kind of concentration were tweaked again and again to favour the owners. In 2018 and then again in 2023, laws were changed to let directors serve longer continuous terms, first up to nine years and later to 12. These changes were never about improving efficiency. They were done to meet the demands of influential people who wanted to hold on to power. Some of these directors lent money to their own business groups on easy terms violating rules and then laundered it abroad. Consequently, those banks are now drowning under the weight of non-performing loans.

Against this record, the reform plan prepared under the interim government was a necessary step towards restoring discipline in the banking sector. It proposed reducing the maximum number of directors from a single family from three to two and shortening the maximum continuous tenure from 12 years to six. To prevent owners from bypassing these limits through extended family members, it also sought to widen the legal definition of family to include in-laws and siblings. The plan further proposed that independent directors make up half of each bank's board and that directors face consequences when companies linked to them default on loans. After the experience of recent years, it is difficult to justify a retreat from these safeguards. Yet, the current administration is considering changes that could once again allow influential business groups to treat banks as their personal piggy banks.

The bankers' association has reportedly defended the proposed changes by claiming that longer tenures preserve experience and that reducing family representation threatens operational stability. Such arguments do not hold. Increasing family representation and director tenures do more to strengthen nepotism and family dominance and open the door to irregularities than any benefit from longer experience could justify. True stability comes from independent oversight and professional management rather than from keeping power inside a closed circle of relatives.

Thus, this current approach clearly undermines the very foundation of good governance and is not good for the banking industry. It is really hard to see how regulators could think allowing denser family control could bring in anything positive when many past irregularities took place through the collusion of board members. Thanks to those outright lootings of the past, Bangladesh has effectively become a global leader in non-performing loans. The present government shows little visible commitment to reverse the situation. Nor is there any clear process in sight to recover the stolen money siphoned out of the country. The effect on the wider economy is already clear and the International Monetary Fund warning that growth may fall below four per cent this year is evidence enough of the weakness that continues to weigh on overall performance.

Those responsible for these decisions should not assume that their actions will carry no consequences. Bangladesh is due to undergo its fourth round of mutual evaluation by the Financial Action Task Force (FATF) in 2027-28 when the country's safeguards against money laundering and other financial crimes will face close scrutiny. After one of the worst episodes of bank looting in history, this assessment will be a serious test of the country's commitment to financial integrity. Although allowing more family members on bank boards or extending directors' tenure would not, by itself, violate FATF standards, weakening safeguards against conflicts of interest and lending abuses could raise concerns about the effectiveness of financial sector oversight. This could be read as enabling the same powerful business families to regain or keep control of banks that were behind the previous lending irregularities. Should that view take hold, grey listing becomes a credible risk, and its costs would fall on the whole economy, not just on the banking sector.​
 

BB to run alternative to SWIFT for local LCs

Mostafizur Rahman . Dhaka

1792974755412.webp


Bangladesh Bank will shift the processing of local back-to-back letters of credit (LCs) from the international SWIFT network to a domestic messaging system next month, aiming to reduce banks’ transaction costs.

BB officials said the system is ready and is expected to become operational next month.

The central bank met commercial banks on October 22 and instructed them to begin trial runs from Sunday.

The new system will handle only back-to-back LCs between banks in Bangladesh and will not affect international payments or communications with foreign banks.

They said that the system will reduce around Tk 75 crore costs for banks annually.

A back-to-back LC is a credit arrangement in which a bank opens a second letter of credit against an existing LC issued in support of an export order. It allows an exporter to purchase raw materials and other supplies needed to fulfil the order without paying the full cost upfront.

For example, a foreign buyer in Europe places an order worth $1 million with a Bangladeshi garment exporter and opens a master LC through its bank.

The exporter needs fabric from a local textile mill to manufacture the garments. The exporter’s bank then opens a back-to-back LC in favour of the textile mill, using the foreign buyer’s LC as security. The mill can supply the fabric against the bank’s payment commitment, while the exporter uses the proceeds from the export order to settle the financing.

Such LCs are central to Bangladesh’s garment industry, as exporters frequently depend on credit to purchase fabric, yarn and accessories before receiving payment from foreign buyers.

Back-to-back LCs do not necessarily involve only two local banks. A foreign bank may issue the master LC, while a Bangladeshi bank opens the second LC for a local supplier. In that case, the transaction involves international banking communications as well as domestic financing.

BB’s new system will replace SWIFT only for messages exchanged between Bangladeshi banks under the local arrangement, not for communications with foreign banks.

SWIFT, or the Society for Worldwide Interbank Financial Telecommunication, is a Belgium-based cooperative that provides a secure, standardised network for banks to exchange financial messages.

It does not itself transfer money; payments are settled through accounts held by banks. Banks pay SWIFT fees for using its services, and these costs may be passed on to customers through LC and messaging charges.

Under the new arrangement, local banks will exchange messages relating to eligible back-to-back LCs through a system operated by BB, avoiding SWIFT charges on those messages.

The central bank will not charge banks for using the domestic system, but the extent of any savings for businesses will depend on whether banks reduce their customer fees.

However, experts have cautioned that a domestic messaging network could become a target for cyberattacks if security controls are inadequate. The system will carry sensitive information about exporters, suppliers, contracts and credit arrangements, making data protection and uninterrupted service important for the garment supply chain.

Experts recommend independent security audits and penetration tests, strong authentication, multiple approvals for transactions, tamper-resistant records, isolated bank connections and continuous monitoring for suspicious activity.

Mashrur Arefin, Managing Director & CEO of City Bank PLC, said local LC messages can be transmitted through Foreign Exchange Transaction Management System (FxTMS) of Bangladesh Bank rather than SWIFT, potentially reducing foreign-currency message transmission fees.

The new system uses message formats similar to SWIFT’s and connects directly to banks’ trade systems, which reduces manual work. Banks must still set up secure links, test the system and bear integration and maintenance costs.

Its message structures and data fields largely follow familiar SWIFT MT templates, including MT 700, MT 707 and MT 799.

API connectivity is intended to support integration with banks’ core trade systems and reduce reliance on separate manual processes, he added.

He said the move does not by itself raise fraud risk. Only authorised head-office staff can access it, the computers are hardened and isolated, the link between banks and BB is private, and only approved IP addresses can connect. Banks will test it by sending LCs to each other before launch.

SWIFT stays for international trade, so exports are unaffected. The main risk is mismatched data between FxTMS and banks’ own systems. Banks and BB should follow international message standards, map data consistently and keep traceable transaction references for reconciliation, he said.​
 

11th Annual Banking Conference begins at BIBM today

The Bangladesh Institute of Bank Management (BIBM) will hold the two-day 11th Annual Banking Conference at its Mirpur-2 premises in Dhaka from today, Wednesday, 28 October 2026. Bangladesh Economic Report

Md Mostaqur Rahman FCMA, Governor of Bangladesh Bank and Chairman of the BIBM Governing Board, will attend the inauguration as Chief Guest, according to a media release.

The inaugural session will take place in the BIBM Auditorium.

Dr. Prashanta Kumar Banerjee, Professor of BIBM and Chair of the Conference Organizing Committee, will deliver the address of welcome.

Dr. Zaidi Sattar, Chairman of the Policy Research Institute of Bangladesh (PRI), will present the keynote speech on “Bangladesh Banking System and Monetary-Fiscal-Trade Policy Coordination for Macroeconomic Stability and Growth.”

The following will speak as Special Guests: Dr. Md. Kabir Ahmed, Deputy Governor, Bangladesh Bank; Mr. Jean Pesme, Division Director, World Bank-Bangladesh and Bhutan; Mr. Abdul Hai Sarker, Chairman, Bangladesh Association of Banks (BAB) and Chairman, Dhaka Bank PLC; Mr. Mashrur Arefin, Managing Director & CEO, City Bank PLC, and Chairman, Association of Bankers Bangladesh Limited (ABB)

Dr. Wahiduddin Mahmud, Distinguished Economist and Former Professor of the Department of Economics, University of Dhaka, will speak as Guest of Honor. Bangladesh Economic Report

The Chief Guest will then address the gathering and formally inaugurate the conference.

Books will be unveiled, and Dr. Md. Ezazul Islam, Director General of BIBM, will deliver a speech as Conference Chair.

The conference will feature 13 plenary sessions and the presentation of 104 research articles.

More than 800 participants are expected, including experts, bankers, researchers and students from home and abroad.

The media partners of the event are DBC, Daily Bonik Barta, Dhaka Stream and The Business Standard.​
 

BB should have equal authority over public and private banks


1793231315769.webp


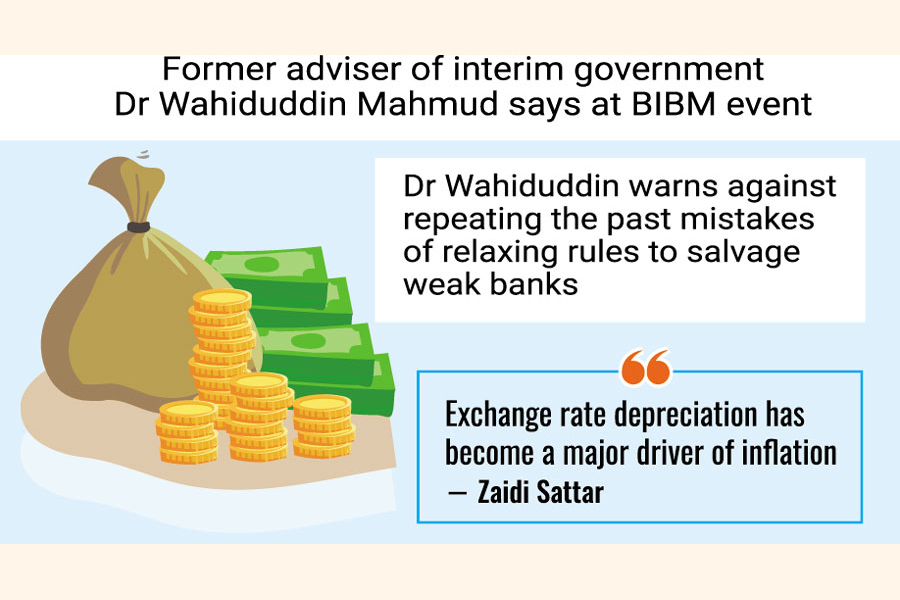
Former adviser of the interim government Dr Wahiduddin Mahmud has said the culture of bank-loan default has transformed into a culture of looting, badly impacting the banking sector.

"That is why the financial sector has reached its current state," he said at the inaugural session of a two-day annual banking conference organised by the Bangladesh Institute of Bank Management (BIBM) in the capital on Wednesday.

Recalling earlier banking reforms, he said considerable efforts had been made to curb loan default through rules and regulations, as well as restore discipline in the sector.

"We managed to come out of the culture of loan default after much effort. We also brought some private banks closer to international standards.

"But afterwards, a culture of bank looting emerged. This is more serious. Money was taken out of banks without following any rules and regulations," he said.

Dr Mahmud said Bangladesh had repeatedly failed to learn from its past banking experience.

Private banks were allowed to be established in the late 1980s without an adequate regulatory framework, he said, resulting in sponsor directors borrowing an amount equivalent to around one-third of some banks' deposits.

"There should have been rules on whether a group or family could control multiple banks. This should come under an anti-trust law. We still do not have an anti-trust or anti-monopoly law," he said.

He also criticised political influence over state-owned banks, saying such institutions had often been used to distribute political patronage.

"Using the banking or financial sector for political patronage is absolutely inappropriate," he said, adding that the Bangladesh Bank should have equal authority over state-owned and private banks.

He warned against repeating the previous policy of relaxing regulations to rescue weak banks.

"Now, to rescue weak banks, we may have to relax some rules again. But where is the guarantee that we will not repeat the same process that brought us to the current situation?" he asked.

Policy Research Institute (PRI) Chairman Dr Zaidi Sattar said the banking sector was facing severe balance sheet stress, marked by exceptionally high non-performing loans (NPLs), provisioning shortfalls, and widespread undercapitalisation.

"Bangladesh can neither restore growth with a crippled banking system nor defeat inflation through high interest rates alone," he said while discussing the country's macroeconomic challenges.

Dr Sattar said exchange rate depreciation has become a major driver of inflation, raising the domestic cost of imported fuel, food, intermediate goods, and capital machinery.

He noted that the taka had depreciated from around Tk 86 per US dollar in May 2022 to about Tk 123, representing roughly 40 per cent depreciation.

He proposed a "compensated depreciation" policy involving tariff reductions to offset the inflationary impact of currency depreciation and improve export competitiveness.

Tariffs could be reduced by 10-20 per cent, he suggested.

Bangladesh Bank Deputy Governor Dr Md Kabir Ahmed said the current banking crisis had developed through a chain of external shocks, reserve depletion, exchange rate pressure, corporate sector stress, and rising banking sector risks.

As non-performing loans increased, capital weakened, provisioning capacity declined, and credit growth slowed, eventually affecting economic growth, he said.

He said the central bank's immediate response had been to rebuild foreign exchange reserves and maintain exchange rate stability.

The banking regulator rebuilt reserves to roughly six months of import cover before the Iran-US conflict and avoided purchasing dollars during the conflict, helping preserve exchange rate stability, he also said.

Dr Ahmed said the banking sector must now be repaired because banks are the principal suppliers of capital to the real economy.

Association of Bankers, Bangladesh (ABB) Chairman and City Bank Managing Director and CEO Masrur Arefin said recent reforms and restructuring of bank boards could pave the way for recovery, but he warned that the damaged culture could not be corrected overnight.

He expressed concern over virtually stagnant credit growth, saying businesses remained reluctant to open large letters of credit for capital machinery and factory expansion.

Sluggish imports and exports also reflected weak economic activity, he said, noting that the Purchasing Managers' Index (PMI) had fallen to 48 from around 57-58 earlier, indicating contraction.

Mr Arefin said business confidence remained weak despite political stability following the election, while cash flow problems were discouraging businesses from expanding.

Bangladesh Association of Banks (BAB) Chairman Abdul Hai Sarker said policies designed for developed economies should not be imposed mechanically on developing countries.

Policy, he said, must reflect a country's level of development, institutional capacity, and national circumstances. Applying developed countries' compliance standards without adequate support could ultimately make developing countries unable to comply, he said.

Chairing the conference, BIBM Director General Dr Md Ezazul Islam called this year's conference theme "both timely and compelling".

High financing costs, subdued investment, infrastructure bottlenecks, and global uncertainty had intensified economic challenges, he said, while weaknesses in governance, asset quality, and accountability had eroded confidence in financial intermediation.

"Banking, above all, rests on trust," he said. "Without it, savings cannot be efficiently channelled into productive investment."

He called for a practical, credible, and balanced reform agenda, including stronger corporate governance, improved asset quality, and capital adequacy. World Bank Division Director for Bangladesh and Bhutan Jean Pesme also spoke in the opening session of the conference.​
 

Banking sector recovery expected by March-April 2027: BB


1793231756502.webp


Bangladesh Bank (BB) is implementing a series of reforms to restore stability in the banking sector, improve governance and normalise investment and credit flows, with visible improvements in banks' financial conditions expected by March-April next year.

"The central bank is prioritising control of non-performing loans (NPLs), assessment of asset quality, addressing capital shortfalls, strengthening corporate governance and improving risk management," said BB Deputy Governor Dr Md Habibur Rahman today (Wednesday), BSS reports.

He made the remarks while speaking as a special guest at the inaugural session of the 11th Annual Banking Conference (ABC) 2026, organised by the Bangladesh Institute of Bank Management (BIBM).

Renowned economist and former interim government adviser Dr Wahiduddin Mahmud, a former professor of economics at Dhaka University, attended the programme as the chief guest.

Other special guests included Jean Pesme , World Bank Division Director for Bangladesh and Bhutan; Mohammad Abdul Hai Sarker, chairman of the Bangladesh Association of Banks (BAB) and Dhaka Bank PLC; and Mashrur Arefin, managing director and CEO of City Bank PLC and chairman of the Association of Bankers, Bangladesh Limited (ABB).

Dr Habibur Rahman said the first phase of measures to address the banking sector's challenges focused on rebuilding foreign exchange reserves, settling outstanding external liabilities and maintaining exchange rate stability.

The target of building foreign exchange reserves sufficient to cover nearly six months of import expenditure has also been achieved, he said.

Drawing lessons from the global financial crisis and the Southeast Asian financial crisis, he said, the central bank is prioritising financial stability, in line with the approach adopted by central banks in other countries.

An initiative has also been taken to amend the Bangladesh Bank Order to strengthen the central bank's role in maintaining financial stability, he added.

Explaining the ongoing banking reforms, the deputy governor said asset quality reviews were being conducted to assess banks' actual financial conditions and restore confidence among depositors and investors.

The reviews have already been completed in 15 banks, while assessments of the remaining banks are progressing with support from the World Bank, he said.

The banking sector's non-performing loan ratio, which stood at 36 percent in December 2025, has declined to 31 percent, he said, expressing hope that it would fall further significantly by December this year.

The Money Loan Court Act and the new Special Asset Management Act would help accelerate the recovery of defaulted loans, he added.

Restoring the financial capacity of state-owned and private banks facing capital shortfalls is another major priority of the central bank, Dr Habibur Rahman said.

The central bank is working with the Finance Ministry on the issue. If the planned measures are implemented as intended, visible improvements in banks' financial conditions are expected by March-April 2027, he said.

He noted that conventional policies alone might not always be sufficient to address a financial crisis, making exceptional measures necessary in certain circumstances.

During the 2008 global financial crisis in the United States, liquidity support and government investment were used to help banks and financial institutions recover. Bangladesh is also focusing on improving banks' financial health, governance and transparency after containing risks, he said.

The deputy governor stressed the need for independent decision-making by bank boards, accountability of management and effective authority for risk management and compliance departments.

He urged banks to make lending decisions based on borrowers' repayment capacity, cash flows and realistic business prospects rather than influence or personal relationships.

Proper loan classification, adequate provisioning and sound capital planning are also essential to restoring discipline in the banking sector, he added.

Dr Habibur Rahman emphasised regular stress testing to strengthen banks' liquidity and capital management.

Banks must assess their capacity to withstand simultaneous shocks, including declining export orders, rising energy costs, exchange rate fluctuations and pressure from deposit withdrawals, he said.

He also called for stronger cybersecurity, measures to prevent digital fraud and improved capacity to ensure uninterrupted customer services.

The central bank is taking an initiative to establish a 'Bank Restructuring and Resolution Fund' to address the problems of weak banks and financial institutions.

The proposed fund would provide an effective and cost-efficient mechanism for resolving distressed institutions without increasing dependence on government funds, he said.

The deputy governor also stressed the need to modernise the central banking system to harness regional economic opportunities.

Initiatives are underway to expand the use of technology in banking, establish performance-based management and promote cashless transactions, he said.

Alongside the existing Bangladesh Electronic Funds Transfer Network (BEFTN), Real Time Gross Settlement (RTGS), National Payment Switch Bangladesh (NPSB) and Bangla QR systems, an inclusive payment system is planned for introduction next year.

The proposed system would make person-to-person digital transactions easier, he said.

Corporate restructuring and related risk management have also been included in future plans to prevent financial distress at large corporate groups from adversely affecting multiple banks.

He further said an initiative was underway to implement a Tk 60,000 crore package by rearranging existing assets and financing within the financial system, without creating excessive inflationary pressure.

Addressing researchers, academics and bankers, Dr Habibur Rahman underscored the importance of evidence-based policymaking, improving loan quality and expanding safe financial inclusion.

He called for continuous monitoring by policymakers, effective resolution of problems in weak institutions and measures to protect depositors' interests.

Banks, meanwhile, must ensure good governance, identify risks at an early stage and provide fair and quality services to customers, he said.

Expressing optimism about the country's economic prospects, the deputy governor said the main objective was to build a banking system capable of harnessing Bangladesh's skilled workforce, entrepreneurs and economic potential.​
 
Back
Top