Bangladesh Defense

Saif
Senior Member
- Joined
- Jan 24, 2024
- Messages
- 21,935
- Likes
- 9,837
- Nation

- Residence
- Axis Group

Private-bank seniors being hired to fill public banks' MD posts
A plan is under active consideration of the government to appoint private commercial banks' senior executives as managing directors in state-owned commercial banks in a management reshuffle. Meanwhile, the top executive posts in some public banks lay vacant following marching orders for the
Private-bank seniors being hired to fill public banks' MD posts
Govt move meant to better manage banking operations, public banks' aspirants fear career blockage

A plan is under active consideration of the government to appoint private commercial banks' senior executives as managing directors in state-owned commercial banks in a management reshuffle.
Meanwhile, the top executive posts in some public banks lay vacant following marching orders for the incumbents, ostensibly as the banks facing various problems.
The move comes after the Ministry of Finance opened the scope for appointing executives from outside the state-owned banks under a recently issued policy, sources have said.
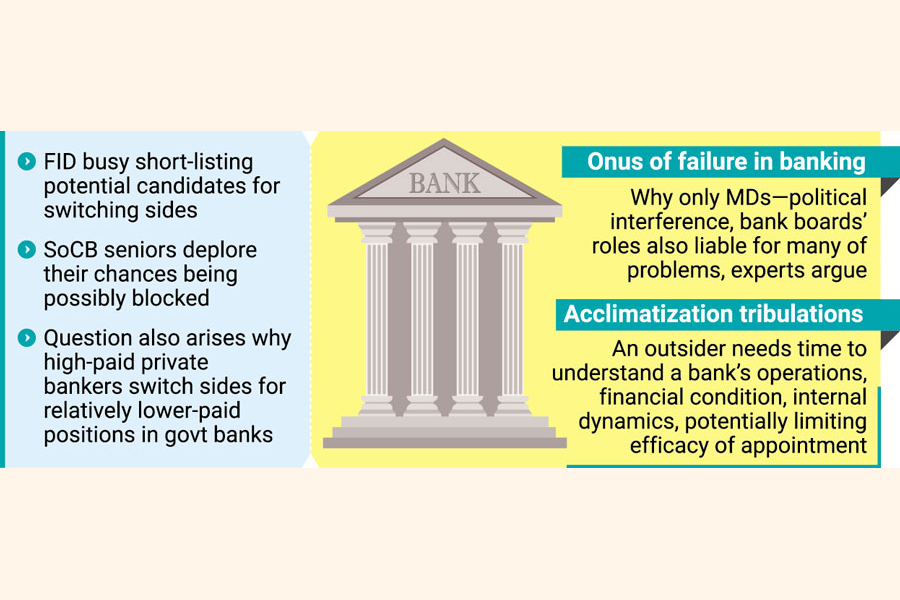
According to the sources, the financial institutions division (FID) under the ministry of finance is busy making a list of potential candidates to be placed to the special committee led by the finance minister for final approval.
Contacted, FID additional secretary for the Central and Commercial Banks Wing Md. Azimuddin Biswas said the government can appoint anyone from existing pool of executives to state-owned banks, such as retired bankers or executives from the private-sector banks.
"There is no bar or restriction that senior executives from privately-operated banks cannot be appointed," he said, adding that a high-powered special committee led by the finance minister will finalise the names before sending it to the central bank for its clearance.
The government reportedly believes that bringing in executives from the private sector could improve corporate governance in state-owned banks and help reduce irregularities and corruption to bring back vibrancy in banking operations.
However, the possible appointments have triggered dissatisfaction among employees at different levels of state banks, who fear that such move could effectively block the career progression of deputy managing directors (DMDs) and other senior officials who have spent years working in the state-owned banking sector and traditionally aspire to become MD.
Bankers, speaking on condition of anonymity, have argued that some private-sector bank executives had failed to prevent their institutions from falling into serious financial distress.
Several private banks are currently undergoing merger processes amid mounting problems in the banking sector, they have pointed out.
A senior executive of a private bank, on condition of not being quoted by name, raised the question why executives drawing significantly higher salaries in private banks would be interested in taking relatively lower-paid positions at state-owned banks.
He said employees had legitimate expectations of reaching the top position after serving their institutions for many years.
"We have served the banks for years. Naturally, we expect to become managing director before retirement. But that opportunity is now being taken away," said one public-sector banker.
Another executive who spent more than 25 years in public banks said that irregularities and corruption in state-owned banks could not be attributed solely to managing directors as political interference and the role of bank boards were also responsible for many of the problems.
"Such appointments could create disorder within state-owned banks. Officials may not readily accept an MD coming from outside. That could ultimately hurt the bank," he told the FE.
He added that an outsider would also need considerable time to understand the bank's operations, financial condition and internal dynamics, potentially limiting the effectiveness of the appointment.
The government recently removed the managing directors of Sonali Bank, Janata Bank and Rupali Bank. Earlier, it had cancelled the remaining terms of the managing directors of BASIC Bank and Agrani Bank.
But the government did not publicly clarify whether the removals were made on political considerations or based on performance assessments.
Govt move meant to better manage banking operations, public banks' aspirants fear career blockage
A plan is under active consideration of the government to appoint private commercial banks' senior executives as managing directors in state-owned commercial banks in a management reshuffle.
Meanwhile, the top executive posts in some public banks lay vacant following marching orders for the incumbents, ostensibly as the banks facing various problems.
The move comes after the Ministry of Finance opened the scope for appointing executives from outside the state-owned banks under a recently issued policy, sources have said.
According to the sources, the financial institutions division (FID) under the ministry of finance is busy making a list of potential candidates to be placed to the special committee led by the finance minister for final approval.
Contacted, FID additional secretary for the Central and Commercial Banks Wing Md. Azimuddin Biswas said the government can appoint anyone from existing pool of executives to state-owned banks, such as retired bankers or executives from the private-sector banks.
"There is no bar or restriction that senior executives from privately-operated banks cannot be appointed," he said, adding that a high-powered special committee led by the finance minister will finalise the names before sending it to the central bank for its clearance.
The government reportedly believes that bringing in executives from the private sector could improve corporate governance in state-owned banks and help reduce irregularities and corruption to bring back vibrancy in banking operations.
However, the possible appointments have triggered dissatisfaction among employees at different levels of state banks, who fear that such move could effectively block the career progression of deputy managing directors (DMDs) and other senior officials who have spent years working in the state-owned banking sector and traditionally aspire to become MD.
Bankers, speaking on condition of anonymity, have argued that some private-sector bank executives had failed to prevent their institutions from falling into serious financial distress.
Several private banks are currently undergoing merger processes amid mounting problems in the banking sector, they have pointed out.
A senior executive of a private bank, on condition of not being quoted by name, raised the question why executives drawing significantly higher salaries in private banks would be interested in taking relatively lower-paid positions at state-owned banks.
He said employees had legitimate expectations of reaching the top position after serving their institutions for many years.
"We have served the banks for years. Naturally, we expect to become managing director before retirement. But that opportunity is now being taken away," said one public-sector banker.
Another executive who spent more than 25 years in public banks said that irregularities and corruption in state-owned banks could not be attributed solely to managing directors as political interference and the role of bank boards were also responsible for many of the problems.
"Such appointments could create disorder within state-owned banks. Officials may not readily accept an MD coming from outside. That could ultimately hurt the bank," he told the FE.
He added that an outsider would also need considerable time to understand the bank's operations, financial condition and internal dynamics, potentially limiting the effectiveness of the appointment.
The government recently removed the managing directors of Sonali Bank, Janata Bank and Rupali Bank. Earlier, it had cancelled the remaining terms of the managing directors of BASIC Bank and Agrani Bank.
But the government did not publicly clarify whether the removals were made on political considerations or based on performance assessments.