[🇧🇩] Energy Security of Bangladesh

[🇧🇩] Energy Security of Bangladesh
819
34K
More threads by Saif

G Bangladesh Defense

Gas erupts during tube-well drilling in Cox’s Bazar

1793143824928.webp


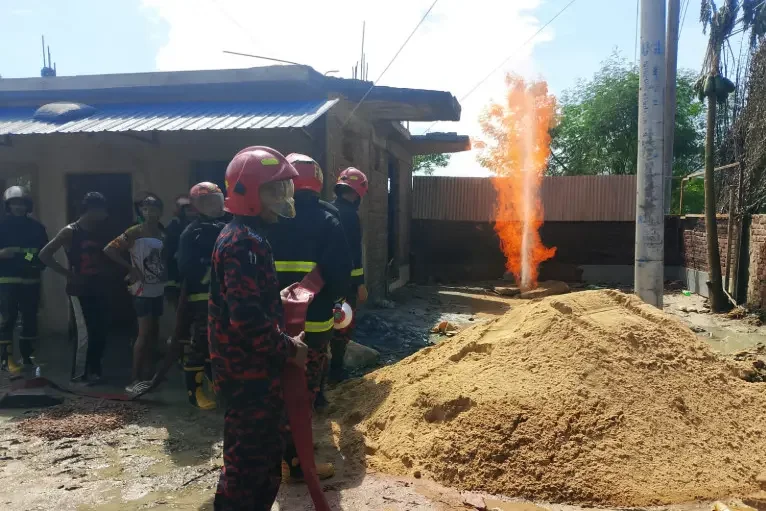
Instead of water, natural gas has started spewing from a 1,000-foot-deep borehole drilled in the Inani area in Ukhia upazila of Cox’s Bazar district.

A fire broke out around 6:00 am on Tuesday in an area near a small bridge at Inani.

Upon receiving the report, three units from the Fire Service arrived at the scene and started working to bring the blaze under control.

Belal Uddin, a supervisor for beach personnel under the district administration at Inani, said that a man named Md Abdullah is constructing a resort on his 20-decimal plot of land at Sikdarpara, Inani. Work on installing a tube-well to provide water for the resort had been going on for the last 15 days. Drilling was halted three days ago after no water was found, even at a depth of approximately 1,000 feet.

Then, at around 6:00 am this morning, gas suddenly began to escape from the borehole at high pressure, igniting upon contact with nearby electrical wires, reports BSS.

Following the incident, three fire service units from Ukhia and Cox’s Bazar Sadar arrived at the scene around 8 am and began efforts to extinguish the fire.

Confirming the incident, Syed Md Morshed Hossain, deputy assistant director of the Cox’s Bazar Fire Service, said, "Our three units are working continuously to bring the fire under control. Additionally, an army fire team has been assisting with the containment efforts since 2:30 pm. The intensity of the fire is heightened by the escaping gas. To prevent any untoward accidents, the electricity supply to the entire area has been temporarily suspended."

Meanwhile, local residents are gripped by intense panic, as the fire has persisted despite repeated attempts to smother it with sandbags, and there are concerns that it could spread further.

Concerned locals have called for the fire to be extinguished promptly and urged a geological survey to determine whether a significant gas reserve exists at the site.​
 

Bangladesh needs a strategy to wean itself off imported gas

Rassiq Aziz Kabir and Ismot Hasnine Masrur E Khuda

1793147082776.webp

Commuters wait in long queues at a refilling station in Dhaka on March 12, 2026. FILE PHOTO: MEHEDI HASAN

Energy has rarely been treated as anything more than a question of tariffs and subsidies in the concurrent policy discourse of Bangladesh. However, the war that began with the US-Israeli strikes on Iran on February 28 and the resulting disruption of shipping through the Strait of Hormuz have changed the scenario. By April, Qatar invoked force majeure on its LNG contracts, diesel stocks fell below 10 days of cover, and Bangladesh had to ration fuel sales. Nearly eight months on, the emergency has settled into a chronic condition. We still rely on imported fuel to keep our power plants, factories and farms running, leaving us exposed to shocks beyond our control. It is now clear that energy is a matter of national security.

The price of this exposure is visible across the economy. By mid-September, Bangladesh was paying nearly $30 per million British thermal units (MMBtu) for spot LNG, almost three times the pre-war rate. Zero Carbon Analytics, an international research group, projected that the country’s annual energy import bill of roughly $12 billion could rise by $4.8 billion, or 40 percent, if the elevated prices persist. The energy ministry projects this year’s LNG subsidy bill at Tk 40,000 crore, nearly triple last year’s payout, while electricity subsidies could reach Tk 50,000 crore. Consumers have not been spared either, as retail electricity prices were raised by 16.68 percent in June. More recently, the World Bank’s forecast cut Bangladesh’s growth to 3.4 percent in FY2026-27, citing a more protracted drag from energy shortages.

The roots of the problem go back almost a decade. In 2018, Bangladesh began importing LNG as a stopgap to address declining domestic gas output, which has since fallen by about 30 percent over six fiscal years. That stopgap has now become a crutch, and an expensive one, with Petrobangla’s LNG import bill rising from Tk 16,505 crore in FY2020-21 to around Tk 59,000 crore in FY2025-26. Domestic fields currently produce around 1,620 million cubic feet per day (mmcfd) of gas against an estimated demand of 3,860 mmcfd. Even with imported LNG, this leaves a shortfall of roughly 32 percent. Domestic production is itself concentrated, with a single field in Habiganj supplying about half of it. Meanwhile, imported fossil fuel now accounts for about 59 percent of our trade deficit.

What makes this dependence dangerous is the level of concentration. Between January 2025 and March 2026, the Middle East supplied 64 percent of our LNG, 69 percent of our LPG, and about 63 percent of our crude oil, as well as accounting for nearly half of over $30 billion in remittances received in FY2025-26. A single shock therefore inflates the import bill while threatening the inflows that pay for it.

Fuel rationing during the Boro season also endangers irrigation and food security. The concentration is physical as well as geographical. All imported LNG enters through just two floating terminals in Moheshkhali, which have been disrupted at least three times in as many years: Cyclone Mocha forced both terminals offline in May 2023; Cyclone Remal reduced capacity for nearly four months in 2024; and a terminal experienced a temporary, partial outage again in July 2026. Each time, the shortfall’s impact spread quickly and was felt across the country.

Japan, which imports almost all of its oil, was able to release supply worth 45 days of consumption from state and private reserves in March. This was possible because stockholding is a legal obligation in the country, rather than an administrative aspiration. By contrast, India’s strategic petroleum reserve, despite having a capacity of 5.33 million tonnes, can meet only about 9.5 days of crude requirement. Bangladesh is in an even weaker position, with no formal strategic fuel reserve at all. A legal obligation on the Bangladesh Petroleum Corporation (BPC) to hold 90 days of stock, phased in as storage expands and with stock levels published every month, should therefore be our first priority.

Bhutan offers a different lesson. Hydropower sold to India is its primary export and a major source of revenue. Bangladesh, by comparison, imports only 40 MW from Nepal and only during June-November, while India has withheld approval for an additional 20 MW, citing transmission constraints. In this regard, Dhaka should actively press New Delhi for a dedicated Bangladesh-Nepal transmission corridor. A four-country power trading agreement among Bangladesh, Bhutan, India and Nepal would also give the government’s Saarc ambitions their first concrete deliverable. At the same time, power imports must also be diversified so that cross-border trade does not simply replace one single-supplier dependence with another.

Meanwhile, more than a decade after settling our maritime boundaries, we have yet to make a major offshore gas discovery, even as India, Myanmar and Pakistan have expanded deepwater exploration. The Offshore Bidding Round 2026, with bids for 26 blocks due by November 30, must not see a repetition of the bidless 2024 round. Petrobangla should release seismic data free to pre-qualified bidders, clear approvals within 90 days through a single window, and reserve a carried stake for Bapex in each contract to keep offshore expertise at home.

Supply contracts need similar reform. Qatar has extended its supply disruption notices to Bangladesh while, in August, 22 cargoes were approved without tender. The recent deal for 117 US LNG cargoes up to 2038 is a start, but diversification must become the rule. Still, diversified contracts will mean little without the capacity to receive them, which is why the government’s decision to fast-track a third floating terminal at Kutubjom must translate into delivery.

Future long-term agreements should cap Gulf-sourced volumes at no more than half of all annual LNG imports, with the balance contracted from the US, Australia or Malaysia, and include supplier substitution clauses. Spot purchases should be made only from a panel of suppliers pre-qualified through an open tender each quarter, with the price and supplier of every emergency cargo disclosed within 30 days.

Finally, none of this will hold without an institutional home. An energy security council under the Prime Minister’s Office, bringing together the energy, finance, foreign and expatriates’ welfare ministries, should run quarterly stress tests against 30-, 90-, and 180-day closures of Hormuz and publish the results.

In 2022, the Russia-Ukraine war triggered fuel price hikes and nationwide load-shedding, a warning we largely failed to heed. Recent weeks offer a further lesson. Only a month after signing a sweeping sanctions law against Russia, the US president announced a deal to import Russian diesel, reversing a policy that was in place since 2022.

Large economies can afford such abrupt turns. Bangladesh cannot. Our contracts and terminals lock in choices for decades, so every decision in this crisis must be weighed carefully.

Rassiq Aziz Kabir is an academic and public policy analyst.

Ismot Hasnine Masrur E Khuda is a researcher and energy policy analyst.​
 

BD holds huge growth potential in clean energy sector


1793231992967.webp


The size of Bangladesh’s domestic market offered considerable growth potential for entrepreneurs, Murray Spence, Australian Trade and Investment Commissioner for South Asia, told the FE.

Australia has a population of around 28 million, compared with Bangladesh’s population of approximately 177 million to 178 million, he noted.

“That’s more than six times the size of our market. So there is great scope for growth,” he said, adding that Australia is looking to partner with Bangladeshi businesses to expand solar power generation, battery storage and energy-management solutions, as the country’s reliance on fossil fuels and difficulties in securing energy supplies create an urgent case for accelerating the clean-energy transition.

An Australian government-funded study has identified 10 potential areas of cooperation in Bangladesh, with Australian companies exploring opportunities to introduce their technologies, expertise and systems through partnerships with local businesses.

“We know that Bangladesh, due to factors beyond its control, is facing an energy crisis, and its reliance on fossil fuels and the current challenges in securing them make this an urgent case,” Murray Spence, Australian Trade and Investment Commissioner for South Asia, told The Financial Express in an interview.

The report, outlining potential projects and challenges in Bangladesh’s renewable energy sector, was launched on Sunday as part of an Australian initiative to deepen business-to-business cooperation and help accelerate the country’s clean-energy transition.

Mr Spence said an Australian delegation comprising eight companies and 10 representatives had visited Bangladesh to assess market opportunities and explore partnerships in solar power, battery storage, rooftop installations, skills development and energy-efficiency solutions.

The delegation includes companies working in residential, commercial, industrial and utility-scale solar power, as well as battery storage and systems designed to improve the efficiency of electricity use.

“We have the technology. We are looking for local partners, and together they can identify projects and determine how to roll them out,” he said, adding that the initiative was at an early stage of assessing which Australian technologies could be adapted to Bangladesh and how they could be deployed.

He stressed that the immediate objective was to establish partnerships rather than commit to direct investment.

The Australian companies could explore different business models, including technology licensing, franchising and joint ventures, depending on the opportunities and their long-term interests in Bangladesh.

Poor-quality solar panels that fail to deliver their advertised output could weaken Bangladesh’s clean-energy transition, an Australian trade official has warned, urging the country to tighten product regulation and establish reliable testing systems as it expands renewable power amid an energy crisis.

Talking to the FE, Murray Spence, Australian Trade and Investment Commissioner for South Asia, said Bangladesh needed stronger oversight to ensure solar equipment installed on homes, businesses and factories performed as promised. He warned that mismatched power ratings could erode consumer confidence, waste investment and limit the contribution of solar power to national energy security.

“I think there needs to be some regulation,” Mr Spence told The Financial Express, suggesting that Bangladesh establish a dedicated testing body or deploy trained personnel to assess solar equipment and monitor its performance.

Australia has developed expertise across the clean-energy value chain, from electricity generation and storage to transmission, grid integration and efficient consumption, he said.

“Australia began its journey 20 years ago in clean energy. We now have the capability to generate electricity, but it is not just about generation. It is also about storing it, transmitting it, integrating it into the grid, and using it efficiently and effectively,” he said.

Some Australian states have achieved periods of electricity generation from 100 per cent renewable sources, while others generate surplus electricity that can be supplied to other parts of the country, he added.

The visiting delegation also includes a company representing one of the world’s largest battery installations developed in Australia, according to Mr Spence.

He said Australian companies could help Bangladesh develop the skills needed to install, operate and maintain rooftop solar systems, while introducing digital and computer-based solutions to monitor performance and identify technical problems.

Such systems could help businesses and households ensure that the electricity generated by solar panels is being used efficiently, he added.

He suggested that Bangladesh could consider establishing or strengthening an authority responsible for testing and regulating solar products installed on residential, commercial and industrial rooftops.

Australian companies could support such efforts by sharing technical expertise, providing training and helping develop systems to assess equipment performance, he said.

Training could also create employment opportunities for local workers in solar installation, cleaning, maintenance and performance monitoring.

Mr Spence said Australian companies would maintain their quality standards while operating in Bangladesh and could help introduce relevant Australian standards and technical practices.

He clarified that Australia was not seeking to influence Bangladesh’s choice of equipment suppliers or prevent it from buying products from China or elsewhere.

“People will buy from wherever they want. It is their choice,” he said, adding that the priority should be to ensure that products meet appropriate quality and performance standards.

The commissioner said Australian representatives had previously met Bangladeshi ministers and officials at the Prime Minister’s Office to share their experience and offer policy recommendations.

Among the issues raised were substantially reducing tariffs on imported solar components and establishing appropriate standards, he said.

He also welcomed Bangladesh’s efforts to introduce policies encouraging investment in battery storage and enabling consumers to use stored electricity when needed, or feed surplus power into the grid where the necessary infrastructure is available.

Mr Spence said the Australian government-funded study would help identify concrete projects and give prospective investors a clearer understanding of the opportunities and challenges in the local market.

The 10 potential areas outlined in the report are intended to provide a basis for discussions with Bangladeshi authorities and business partners, with the aim of translating broad clean-energy ambitions into practical projects.

Mr Spence said he hoped that by the time another delegation visited Bangladesh next year, some of the companies currently exploring the market would already be working with local partners on projects.

The initiative, he said, was intended to match Australian technology and expertise with Bangladesh’s renewable-energy needs, while allowing businesses on both sides to determine which partnerships and projects were commercially viable.​
 

Bangladesh cannot wait two years to manage its energy demand

M Niaz Asadullah


1793320463088.webp

FILE VISUAL: STAR

Finance Minister Amir Khasru Mahmud Chowdhury recently acknowledged that Bangladesh needs at least two years to stabilise its energy sector and the wider economy. The admission is sobering, but also useful. It raises a question that deserves more attention: if adequate supply cannot be restored soon, how will the country manage with scarce energy during the next two years?

The government does have plans for new wells, production-sharing contracts (PSCs), solar generation, LNG terminals, and an energy hub near Khulna. Japan’s $317 million Emergency Support Loan, highlighted during Prime Minister Tarique Rahman’s Tokyo visit, is also relevant as it supports economic and energy reforms, not a specific power plant. But these initiatives will be helpful in the medium term at best. Wells, terminals, pipelines, and renewable projects require time, capital, and capable institutions. Until they deliver, the government must decide who receives scarce energy, at what price, and with which level of reliability.

As things stand, Bangladesh is not short of installed power plants. A recent Panam Institute policy note estimates the country’s grid capacity at about 28,900 MW, against a record generation of only 17,200 MW. Its message is that the system is short of gas and money, not power plants. The same note reports that domestic gas production has been falling since 2016-17, while imports rose from contributing 47.7 percent to 62.5 percent of primary energy between 2020-21 and 2024-25.

My recent conversation with a leading industrialist in the energy business pushed me beyond this familiar supply-side diagnosis. His argument was that the deeper problem lies in industrial policy. For decades, extraordinarily cheap domestic gas influenced where firms invested, what they produced, and how much they focused on energy efficiency. Bangladesh did not pursue textbook import-substituting industrialisation throughout the 1980s and 1990s; those decades also brought trade liberalisation and the rise of export-oriented garments. But policies protected and promoted domestic processing industries such as steel re-rolling, fertiliser, ceramics, glass, cement, and textiles while gas and electricity remained priced below their full economic cost.

That model could appear successful while domestic gas was plentiful, but it is harder to justify when the marginal unit is imported LNG. An industry that saves one dollar of imports but requires more than a dollar of imported fuel, foreign exchange, and public subsidy is not genuinely saving foreign exchange. It is merely replacing one import bill with another, while part of the cost is concealed in the accounts of Petrobangla, the Bangladesh Power Development Board, and in the national budget.

This does not make steel, ceramics, or glass inherently undesirable. They create jobs and supply essential inputs. The relevant question is whether a new project or major expansion can compete when charged the full, long-run cost of reliable energy. Existing workers and capital cannot be moved without serious disruption. New investment, however, should not receive an open-ended entitlement to subsidised energy.

The allocation problem is already substantial. Industries directly consume about 19 percent of Bangladesh’s gas, while captive power generation inside factories accounts for another 17 percent—together more than one-third of supply, according to the Panam Institute policy note. However, the rules governing how shortages are distributed among grid power, industrial processes, captive generation, fertiliser production, and households remain unclear to the public. In practice, allocation is determined by pressure fluctuations, unplanned outages, administrative discretion, and political access. This is industrial policy by default, rather than by design.

This is where I partly agree with former energy adviser Muhammad Fouzul Kabir Khan’s warning that politicians and their business associates helped create today’s gas crisis. He pointed to unnecessary generation capacity, promises of industrial gas connections when gas was unavailable, and connections awarded through corruption. My argument is complementary but broader: even without an illegal transaction, a policy regime can create the wrong industrial structure when it socialises energy costs while privatising the returns.

Additionally, Professor Anu Muhammad’s recent diagnosis in this newspaper emphasises imported-energy dependence, weak national capability, and the political interests surrounding large projects. Here, a comparison with Malaysia is especially instructive. Malaysia built Petronas into a capable national institution rather than treating lack of domestic capacity as a permanent excuse. Bangladesh must likewise strengthen Bapex and Petrobangla while using foreign firms for capital and specialised knowledge under transparent contracts. But stronger supply institutions still need a disciplined demand policy.

For the next two years, grid management must therefore become an explicit part of industrial policy. The government should publish and enforce clear rules for rationing gas and electricity during shortages; introduce predictable time-of-use tariffs for large consumers; replace arbitrary interruptions with scheduled curtailments; and set public reliability standards for industrial zones. Efficient exporters should be able to plan production rather than discover their effective energy allocation through the duration of an outage. Major sectors should also be assessed for energy intensity, value added, employment, and net foreign-exchange contribution. Any subsidy that remains should be transparently accounted for in the budget, carry a time limit, and be justified by measurable economic benefits.

Over the longer term, new energy-intensive production should cluster near ports, fuel storage, regasification facilities, renewable resources, and common utilities. “Off the national grid” should not mean thousands of unregulated diesel generators, but rather serviced industrial-energy zones using dedicated generation, cogeneration, direct contracts, or transparently priced grid connections. The most energy-intensive stages may sometimes be better located in energy-abundant economies such as Malaysia, while fabrication, distribution, and higher-value activities remain in Bangladesh. Temporary duty relief for heavy fuel oil may ease an emergency, but it should be time-bound and tied to efficiency and emissions standards rather than becoming another permanent subsidy.

The costs of this model are now becoming harder to avoid. Cheap domestic gas helped generate profits and keep input costs low, but it also weakened incentives to explore, conserve, and invest in efficient machinery. The same business leaders who benefitted from that model for decades now find themselves grappling with unreliable supplies and the high cost of imported LNG.

The finance minister’s two-year timetable should be treated as more than a forecast; it should be viewed as a deadline for replacing implicit rationing with transparent demand management.

Bangladesh must accelerate exploration, renewable energy, and import infrastructure while also deciding which uses of scarce energy generate enough social and economic value to justify their cost. Otherwise, the country will continue allocating energy through outages, influence, and inherited privilege.

Dr M Niaz Asadullah is professor of economics at Dhaka University and a visiting professor at the University of Reading in the UK.​
 
Back
Top