


 Bangladesh Defense

Saif
Senior Member
- Joined
- Jan 24, 2024
- Messages
- 21,186
- Likes
- 9,688
- Nation

- Residence
- Axis Group

Growth in NPLs weakening Bangladesh's banking sector: Experts
The growing trend of non-performing loans (NPLs) in Bangladesh's banking sector is placing severe pressure on the nation's financial system, with default loans now exceeding 32 percent of total disbursements and disrupting the natural cycle of credit recycling. National Professor Dr. Mahbub Ullah,
Growth in NPLs weakening Bangladesh's banking sector: Experts
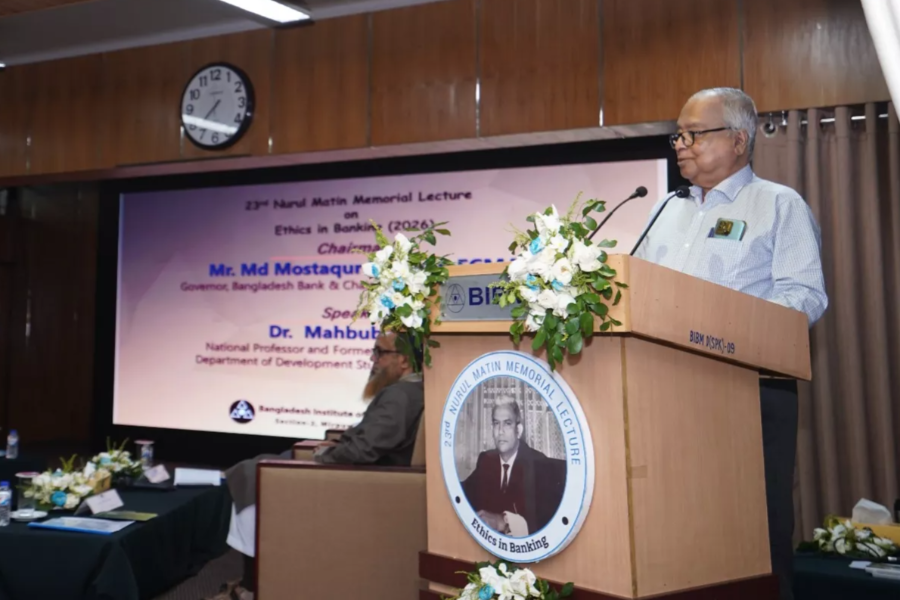
The growing trend of non-performing loans (NPLs) in Bangladesh's banking sector is placing severe pressure on the nation's financial system, with default loans now exceeding 32 percent of total disbursements and disrupting the natural cycle of credit recycling.
Mahbub Ullah, former Professor and Chairman of the Department of Development Studies at University of Dhaka, highlighted these concerns while delivering the 23rd Nurul Matin Memorial Lecture on "Ethics in Banking," organized by the Bangladesh Institute of Bank Management (BIBM) on Saturday, reports UNB.
Bangladesh Bank Governor and Chairman of the BIBM Governing Board, Md Mostaqur Rahman, presided over the event. BIBM Director General Dr. Md. Ezazul Islam delivered the welcome address, while Professor and Director (Research, Development and Consultancy) Md. Shihab Uddin Khan offered the vote of thanks.
In his memorial lecture, Dr. Mahbub Ullah observed that the core engine of the banking system—the continuous recycling of loan funds through deposit collection, lending, and reinvestment—has been severely disrupted. Because a significant portion of disbursed loans is not returning on time, banks are facing severe liquidity pressures and constrained lending capacity.
He pointed out that prolonged financial losses and mounting NPLs have left several banks struggling to maintain required capital reserves under international Basel-II standards. Consequently, even solvent institutions are adopting hyper-cautious lending postures, leaving eligible entrepreneurs and industrial enterprises starved of working capital and investment financing—a scenario that threatens national production, employment, and overall economic growth.
Dr. Mahbub Ullah warned that without sustainable measures, systemic risks will escalate, calling for immediate good governance, ethics, accountability, and proper risk management in loan approval and recovery processes.
Presiding over the function, Bangladesh Bank Governor Md Mostaqur Rahman emphasized that a bank's true strength relies not just on capital, technology, or liquidity, but fundamentally on public trust. He urged bankers to uphold the highest professional and ethical standards to safeguard depositor confidence.
BIBM Director General Dr. Md. Ezazul Islam stressed that banking decisions impact the broader economy because banks handle public funds. He noted that board members and top executives must lead by example to establish a culture of integrity, transparency, and accountability across financial institutions.
Concluding the session, BIBM Director Md. Shihab Uddin Khan stated that ongoing banking sector reforms aim not merely to keep troubled banks afloat, but to build a robust, governance-driven financial architecture that protects depositors, directs credit toward productive sectors, and ensures operational transparency.
The lecture was attended by economists, senior bankers, academics, and representatives from various professional sectors.
The growing trend of non-performing loans (NPLs) in Bangladesh's banking sector is placing severe pressure on the nation's financial system, with default loans now exceeding 32 percent of total disbursements and disrupting the natural cycle of credit recycling.
Mahbub Ullah, former Professor and Chairman of the Department of Development Studies at University of Dhaka, highlighted these concerns while delivering the 23rd Nurul Matin Memorial Lecture on "Ethics in Banking," organized by the Bangladesh Institute of Bank Management (BIBM) on Saturday, reports UNB.
Bangladesh Bank Governor and Chairman of the BIBM Governing Board, Md Mostaqur Rahman, presided over the event. BIBM Director General Dr. Md. Ezazul Islam delivered the welcome address, while Professor and Director (Research, Development and Consultancy) Md. Shihab Uddin Khan offered the vote of thanks.
In his memorial lecture, Dr. Mahbub Ullah observed that the core engine of the banking system—the continuous recycling of loan funds through deposit collection, lending, and reinvestment—has been severely disrupted. Because a significant portion of disbursed loans is not returning on time, banks are facing severe liquidity pressures and constrained lending capacity.
He pointed out that prolonged financial losses and mounting NPLs have left several banks struggling to maintain required capital reserves under international Basel-II standards. Consequently, even solvent institutions are adopting hyper-cautious lending postures, leaving eligible entrepreneurs and industrial enterprises starved of working capital and investment financing—a scenario that threatens national production, employment, and overall economic growth.
Dr. Mahbub Ullah warned that without sustainable measures, systemic risks will escalate, calling for immediate good governance, ethics, accountability, and proper risk management in loan approval and recovery processes.
Presiding over the function, Bangladesh Bank Governor Md Mostaqur Rahman emphasized that a bank's true strength relies not just on capital, technology, or liquidity, but fundamentally on public trust. He urged bankers to uphold the highest professional and ethical standards to safeguard depositor confidence.
BIBM Director General Dr. Md. Ezazul Islam stressed that banking decisions impact the broader economy because banks handle public funds. He noted that board members and top executives must lead by example to establish a culture of integrity, transparency, and accountability across financial institutions.
Concluding the session, BIBM Director Md. Shihab Uddin Khan stated that ongoing banking sector reforms aim not merely to keep troubled banks afloat, but to build a robust, governance-driven financial architecture that protects depositors, directs credit toward productive sectors, and ensures operational transparency.
The lecture was attended by economists, senior bankers, academics, and representatives from various professional sectors.


