Bangladesh Defense

Saif
Senior Member
- Jan 24, 2024
- 21,494
- 9,744
- Nation

- Residence
- Axis Group


Bangladesh’s coal turn is a fresh bad sign for LNG exporters
Bangladesh should be one of the global LNG industry’s success stories, but instead it is a warning sign.
Bangladesh’s coal turn is a fresh bad sign for LNG exporters
REUTERS, Littleton
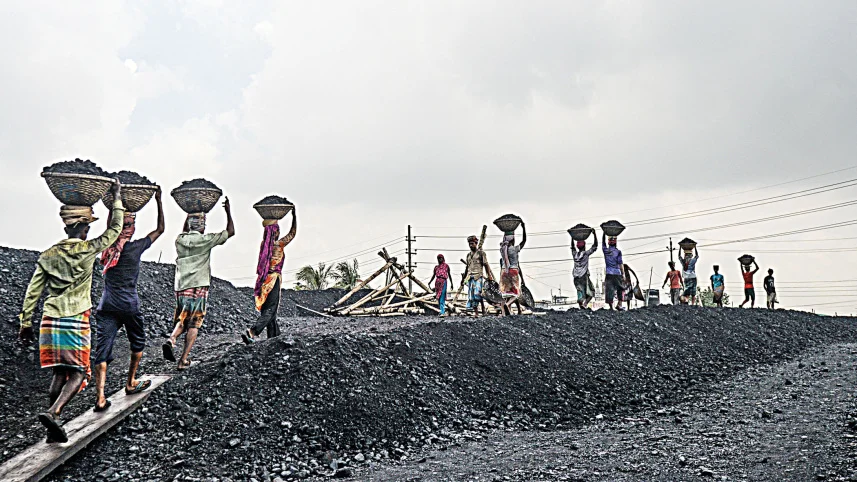
Labourers unload coal from a cargo ship in Dhaka. Coal-fired electricity generation overtook gas-fired generation for the first time this summer in Bangladesh, data from Ember shows. Photo: AFP/FILE
Bangladesh should be one of the global LNG industry’s success stories, but instead it is a warning sign.
Few countries better fit the profile of a future liquefied natural gas growth market.
Electricity demand is rising, domestic gas reserves are falling, and policymakers have invested heavily in LNG import infrastructure to bridge the gap.
For years, those trends helped make Bangladesh a veritable poster child among LNG bulls who argued that rapidly growing Asian economies would underpin LNG demand growth for decades.
Instead, Bangladesh has crossed a milestone that should give LNG investors pause.
Coal-fired electricity generation overtook gas-fired generation for the first time this summer, data from Ember shows, marking a dramatic shift for a country where gas previously accounted for over 90 percent of electricity supplies.
Coal-fired electricity output was 3.92 terawatt hours (TWh) in July, compared to 3.66 TWh of generation from gas-fired plants.
That flip is significant because it has implications for gas use trends across the broader developing world.
COAL COMPETITION
The LNG industry’s growth story rests on a relatively small group of markets.
Demand in Europe is expected to flatten or decline over time as renewables expand.
Japan and South Korea remain major gas importers but both have more new nuclear power generation capacity under construction than gas-fired capacity, according to Global Energy Monitor (GEM), which should limit gas-fired growth.
China remains important, but its energy strategy is also mainly focused on developing domestic clean energy supplies and limiting fossil fuel import reliance.
That leaves emerging Asia, where countries such as Bangladesh, Pakistan, Vietnam and the Philippines have long been viewed as the next generation of LNG buyers.
Those countries are expected to account for much of the growth needed to absorb the massive wave of LNG export capacity being built in the United States, Qatar and elsewhere.
The problem is that these countries are also among the world’s most price-sensitive energy consumers.
Bangladesh’s latest power mix data illustrates the challenge.
Despite expanding access to LNG imports, gas is losing market share to cheaper coal.
That is the opposite of what LNG bulls need to see.
ECONOMIC PAIN
The shift in Bangladesh’s power mix is primarily driven by costs.
Developing economies need reliable electricity, but it needs to be cheap and abundant enough to support industrial growth and expanding urban populations.
In many cases, those priorities outweigh concerns about emissions, and put LNG at a disadvantage.
Unlike domestic energy sources, LNG exposes buyers to global fuel markets.
And following the outbreak of Russia’s war with Ukraine in 2022 and the US and Israeli war with Iran in 2026, global gas buyers have received the painful message that gas imports can get very expensive.
Since the first US and Israeli strikes against Iran in late February, Asian LNG prices have surged from around $11 per million British thermal units (MMBtu) to over $25/MMBtu, dealing a stinging blow to cost-sensitive buyers, LSEG data shows.
Of course, coal carries its own risks, but remains substantially cheaper in Asia at the equivalent of around $6.50/MMBtu for supplies from Australia and nearer $5.00/MMBtu from Indonesia, according to LSEG.
And when governments are trying to keep electricity affordable, those considerations matter.
BROADER MESSAGE
What makes Bangladesh notable is that it appears to be part of a broader pattern.
Several Asian countries have registered steady declines in natural gas’s share of their generation mixes in recent years, including Pakistan and India, which were also viewed as high-potential LNG markets.
Even in Japan, one of the world’s largest LNG importers, gas’s share of the electricity mix has declined from over 40 percent in 2020 to around 28 percent so far this year, Ember data shows.
China is also registering declining gas intensity in power generation.
Despite becoming the world’s largest LNG importer, gas remains only a marginal contributor in China’s electricity production, accounting for around 3 percent of the generation mix so far in 2026. These declines in gas reliance for power generation in key Asian markets undermine arguments that rising electricity demand automatically triggers rising gas consumption.
Indeed, across much of Asia, gas is finding itself squeezed between rapidly growing renewable power and a coal sector that remains difficult to dislodge.
STAYING POWER
Much of the energy-transition debate was previously framed around the idea that gas would gradually displace coal in emerging markets, before being displaced itself by renewables and batteries.
But those discussions overlook the fact that many power operators across Asia remain in no rush to replace coal systems that they have spent decades building and remain cheap to operate.
As a result, every new LNG cargo must justify its cost against a fuel that many developing countries prefer on cost and reliability grounds.
The result is a challenging commercial reality for the LNG export sector.
While wealthy economies may value gas for its emissions advantages and flexibility, lower-income economies often place a higher premium on affordability.
That creates an uncomfortable mismatch between where LNG suppliers need demand growth and where LNG can most easily compete.
WARNING SIGNS
None of this means LNG demand is about to collapse.
Global gas consumption continues to grow in many markets, and new import infrastructure continues to be built.
But Bangladesh offers a valuable reminder that future demand is unlikely to be as automatic as some projections assume.
The world’s LNG industry is currently investing billions of dollars in new export capacity based on the assumption that developing economies will steadily increase gas consumption as their electricity systems expand.
Bangladesh’s experience highlights that gas use has the potential to follow a declining trajectory instead, and may lead LNG investors to ask how many other countries may follow similar paths.
REUTERS, Littleton
Labourers unload coal from a cargo ship in Dhaka. Coal-fired electricity generation overtook gas-fired generation for the first time this summer in Bangladesh, data from Ember shows. Photo: AFP/FILE
Bangladesh should be one of the global LNG industry’s success stories, but instead it is a warning sign.
Few countries better fit the profile of a future liquefied natural gas growth market.
Electricity demand is rising, domestic gas reserves are falling, and policymakers have invested heavily in LNG import infrastructure to bridge the gap.
For years, those trends helped make Bangladesh a veritable poster child among LNG bulls who argued that rapidly growing Asian economies would underpin LNG demand growth for decades.
Instead, Bangladesh has crossed a milestone that should give LNG investors pause.
Coal-fired electricity generation overtook gas-fired generation for the first time this summer, data from Ember shows, marking a dramatic shift for a country where gas previously accounted for over 90 percent of electricity supplies.
Coal-fired electricity output was 3.92 terawatt hours (TWh) in July, compared to 3.66 TWh of generation from gas-fired plants.
That flip is significant because it has implications for gas use trends across the broader developing world.
COAL COMPETITION
The LNG industry’s growth story rests on a relatively small group of markets.
Demand in Europe is expected to flatten or decline over time as renewables expand.
Japan and South Korea remain major gas importers but both have more new nuclear power generation capacity under construction than gas-fired capacity, according to Global Energy Monitor (GEM), which should limit gas-fired growth.
China remains important, but its energy strategy is also mainly focused on developing domestic clean energy supplies and limiting fossil fuel import reliance.
That leaves emerging Asia, where countries such as Bangladesh, Pakistan, Vietnam and the Philippines have long been viewed as the next generation of LNG buyers.
Those countries are expected to account for much of the growth needed to absorb the massive wave of LNG export capacity being built in the United States, Qatar and elsewhere.
The problem is that these countries are also among the world’s most price-sensitive energy consumers.
Bangladesh’s latest power mix data illustrates the challenge.
Despite expanding access to LNG imports, gas is losing market share to cheaper coal.
That is the opposite of what LNG bulls need to see.
ECONOMIC PAIN
The shift in Bangladesh’s power mix is primarily driven by costs.
Developing economies need reliable electricity, but it needs to be cheap and abundant enough to support industrial growth and expanding urban populations.
In many cases, those priorities outweigh concerns about emissions, and put LNG at a disadvantage.
Unlike domestic energy sources, LNG exposes buyers to global fuel markets.
And following the outbreak of Russia’s war with Ukraine in 2022 and the US and Israeli war with Iran in 2026, global gas buyers have received the painful message that gas imports can get very expensive.
Since the first US and Israeli strikes against Iran in late February, Asian LNG prices have surged from around $11 per million British thermal units (MMBtu) to over $25/MMBtu, dealing a stinging blow to cost-sensitive buyers, LSEG data shows.
Of course, coal carries its own risks, but remains substantially cheaper in Asia at the equivalent of around $6.50/MMBtu for supplies from Australia and nearer $5.00/MMBtu from Indonesia, according to LSEG.
And when governments are trying to keep electricity affordable, those considerations matter.
BROADER MESSAGE
What makes Bangladesh notable is that it appears to be part of a broader pattern.
Several Asian countries have registered steady declines in natural gas’s share of their generation mixes in recent years, including Pakistan and India, which were also viewed as high-potential LNG markets.
Even in Japan, one of the world’s largest LNG importers, gas’s share of the electricity mix has declined from over 40 percent in 2020 to around 28 percent so far this year, Ember data shows.
China is also registering declining gas intensity in power generation.
Despite becoming the world’s largest LNG importer, gas remains only a marginal contributor in China’s electricity production, accounting for around 3 percent of the generation mix so far in 2026. These declines in gas reliance for power generation in key Asian markets undermine arguments that rising electricity demand automatically triggers rising gas consumption.
Indeed, across much of Asia, gas is finding itself squeezed between rapidly growing renewable power and a coal sector that remains difficult to dislodge.
STAYING POWER
Much of the energy-transition debate was previously framed around the idea that gas would gradually displace coal in emerging markets, before being displaced itself by renewables and batteries.
But those discussions overlook the fact that many power operators across Asia remain in no rush to replace coal systems that they have spent decades building and remain cheap to operate.
As a result, every new LNG cargo must justify its cost against a fuel that many developing countries prefer on cost and reliability grounds.
The result is a challenging commercial reality for the LNG export sector.
While wealthy economies may value gas for its emissions advantages and flexibility, lower-income economies often place a higher premium on affordability.
That creates an uncomfortable mismatch between where LNG suppliers need demand growth and where LNG can most easily compete.
WARNING SIGNS
None of this means LNG demand is about to collapse.
Global gas consumption continues to grow in many markets, and new import infrastructure continues to be built.
But Bangladesh offers a valuable reminder that future demand is unlikely to be as automatic as some projections assume.
The world’s LNG industry is currently investing billions of dollars in new export capacity based on the assumption that developing economies will steadily increase gas consumption as their electricity systems expand.
Bangladesh’s experience highlights that gas use has the potential to follow a declining trajectory instead, and may lead LNG investors to ask how many other countries may follow similar paths.