[🇧🇩] Energy Security of Bangladesh

[🇧🇩] Energy Security of Bangladesh
790
31K
More threads by Saif

G Bangladesh Defense

Bangladesh’s coal turn is a fresh bad sign for LNG exporters

REUTERS, Littleton
1790986662764.webp

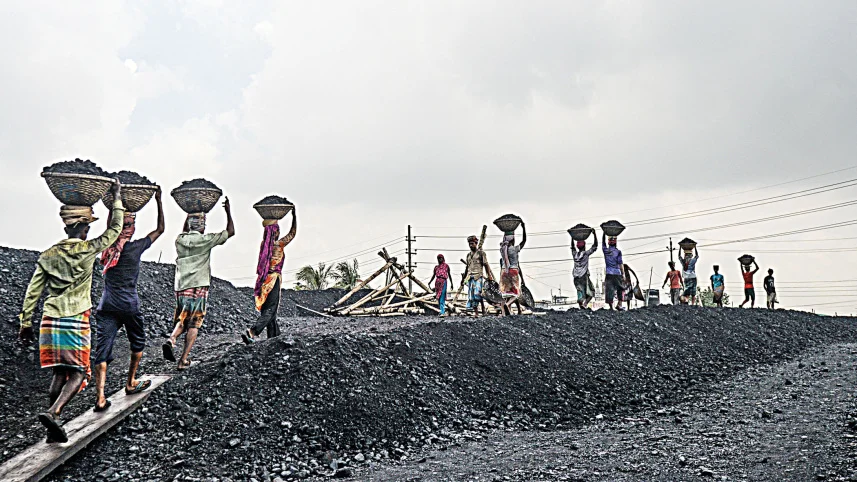
Labourers unload coal from a cargo ship in Dhaka. Coal-fired electricity generation overtook gas-fired generation for the first time this summer in Bangladesh, data from Ember shows. Photo: AFP/FILE

Bangladesh should be one of the global LNG industry’s success stories, but instead it is a warning sign.

Few countries better fit the profile of a future liquefied natural gas growth market.

Electricity demand is rising, domestic gas reserves are falling, and policymakers have invested heavily in LNG import infrastructure to bridge the gap.

For years, those trends helped make Bangladesh a veritable poster child among LNG bulls who argued that rapidly growing Asian economies would underpin LNG demand growth for decades.

Instead, Bangladesh has crossed a milestone that should give LNG investors pause.

Coal-fired electricity generation overtook gas-fired generation for the first time this summer, data from Ember shows, marking a dramatic shift for a country where gas previously accounted for over 90 percent of electricity supplies.

Coal-fired electricity output was 3.92 terawatt hours (TWh) in July, compared to 3.66 TWh of generation from gas-fired plants.

That flip is significant because it has implications for gas use trends across the broader developing world.

COAL COMPETITION

The LNG industry’s growth story rests on a relatively small group of markets.

Demand in Europe is expected to flatten or decline over time as renewables expand.

Japan and South Korea remain major gas importers but both have more new nuclear power generation capacity under construction than gas-fired capacity, according to Global Energy Monitor (GEM), which should limit gas-fired growth.

China remains important, but its energy strategy is also mainly focused on developing domestic clean energy supplies and limiting fossil fuel import reliance.

That leaves emerging Asia, where countries such as Bangladesh, Pakistan, Vietnam and the Philippines have long been viewed as the next generation of LNG buyers.

Those countries are expected to account for much of the growth needed to absorb the massive wave of LNG export capacity being built in the United States, Qatar and elsewhere.

The problem is that these countries are also among the world’s most price-sensitive energy consumers.

Bangladesh’s latest power mix data illustrates the challenge.

Despite expanding access to LNG imports, gas is losing market share to cheaper coal.

That is the opposite of what LNG bulls need to see.

ECONOMIC PAIN

The shift in Bangladesh’s power mix is primarily driven by costs.

Developing economies need reliable electricity, but it needs to be cheap and abundant enough to support industrial growth and expanding urban populations.

In many cases, those priorities outweigh concerns about emissions, and put LNG at a disadvantage.

Unlike domestic energy sources, LNG exposes buyers to global fuel markets.

And following the outbreak of Russia’s war with Ukraine in 2022 and the US and Israeli war with Iran in 2026, global gas buyers have received the painful message that gas imports can get very expensive.

Since the first US and Israeli strikes against Iran in late February, Asian LNG prices have surged from around $11 per million British thermal units (MMBtu) to over $25/MMBtu, dealing a stinging blow to cost-sensitive buyers, LSEG data shows.

Of course, coal carries its own risks, but remains substantially cheaper in Asia at the equivalent of around $6.50/MMBtu for supplies from Australia and nearer $5.00/MMBtu from Indonesia, according to LSEG.

And when governments are trying to keep electricity affordable, those considerations matter.

BROADER MESSAGE

What makes Bangladesh notable is that it appears to be part of a broader pattern.

Several Asian countries have registered steady declines in natural gas’s share of their generation mixes in recent years, including Pakistan and India, which were also viewed as high-potential LNG markets.

Even in Japan, one of the world’s largest LNG importers, gas’s share of the electricity mix has declined from over 40 percent in 2020 to around 28 percent so far this year, Ember data shows.

China is also registering declining gas intensity in power generation.

Despite becoming the world’s largest LNG importer, gas remains only a marginal contributor in China’s electricity production, accounting for around 3 percent of the generation mix so far in 2026. These declines in gas reliance for power generation in key Asian markets undermine arguments that rising electricity demand automatically triggers rising gas consumption.

Indeed, across much of Asia, gas is finding itself squeezed between rapidly growing renewable power and a coal sector that remains difficult to dislodge.

STAYING POWER

Much of the energy-transition debate was previously framed around the idea that gas would gradually displace coal in emerging markets, before being displaced itself by renewables and batteries.

But those discussions overlook the fact that many power operators across Asia remain in no rush to replace coal systems that they have spent decades building and remain cheap to operate.

As a result, every new LNG cargo must justify its cost against a fuel that many developing countries prefer on cost and reliability grounds.

The result is a challenging commercial reality for the LNG export sector.

While wealthy economies may value gas for its emissions advantages and flexibility, lower-income economies often place a higher premium on affordability.

That creates an uncomfortable mismatch between where LNG suppliers need demand growth and where LNG can most easily compete.

WARNING SIGNS

None of this means LNG demand is about to collapse.

Global gas consumption continues to grow in many markets, and new import infrastructure continues to be built.

But Bangladesh offers a valuable reminder that future demand is unlikely to be as automatic as some projections assume.

The world’s LNG industry is currently investing billions of dollars in new export capacity based on the assumption that developing economies will steadily increase gas consumption as their electricity systems expand.

Bangladesh’s experience highlights that gas use has the potential to follow a declining trajectory instead, and may lead LNG investors to ask how many other countries may follow similar paths.​
 

Experts suggest for long-term policy certainty
Prothom Alo English Desk

1791068887773.webp


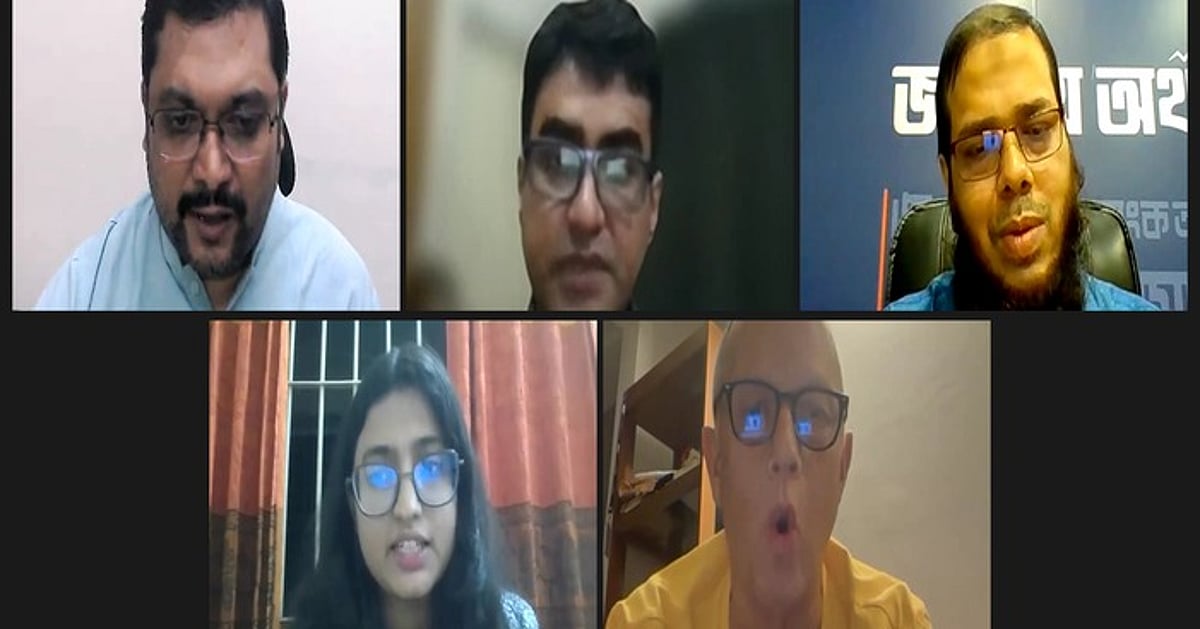
A webinar titled “Bangladesh's Renewable Energy Transition: Closing the Gap to 2030, and the Economic Opportunity Ahead” was organised by the Dacca Institute of Research and Analytics (daira) on Friday to discuss Bangladesh’s renewable energy targets. Collected

A webinar titled “Bangladesh's Renewable Energy Transition: Closing the Gap to 2030, and the Economic Opportunity Ahead” was organised by the Dacca Institute of Research and Analytics (daira) on Friday to discuss Bangladesh’s renewable energy targets, the challenges of implementation, and the policy and infrastructure requirements for accelerating the country’s transition toward renewable energy, says a press release.

Speakers at the webinar highlighted the existing gap between Bangladesh’s renewable energy ambitions and its current capacity to deliver them.

The discussion focused on the need for grid modernisation, energy storage, reliable and accessible energy data, institutional coordination, private-sector investment, and long-term policy certainty.

Speakers also examined the economic and energy-security implications of Bangladesh’s continued dependence on imported fossil fuels.

The session began with a presentation of a policy brief by daira researcher Suborna Akther Laboni. The presentation highlighted that renewable energy currently accounts for approximately 2.3 per cent of Bangladesh’s grid electricity, while the government has set a target of achieving a 20 per cent renewable energy share by 2030.

The presentation noted that solar power costs approximately Tk 9.5 per unit, compared with around Tk 25 per unit for oil-fired generation, highlighting the economic potential of renewable energy.

The presentation further noted that only around 358 MW of renewable energy capacity was under construction as of February 2026, while approximately 760 MW would need to be added annually to remain on track toward the 2030 target.

Meeting the target would require an estimated US$933–980 million in annual investment through 2030. The presentation also highlighted the employment potential of rooftop solar, which generates approximately 26.6 jobs per MW, compared with around 2.1 jobs per MW for utility-scale solar.

The policy brief also examined the challenges surrounding Bangladesh’s electricity grid and renewable energy financing. It noted that a US$515 million World Bank grid programme was rated 'moderately unsatisfactory' in December 2024, having enabled approximately 0.04 GW of renewable energy capacity against a 0.15 GW target.

The presentation also discussed recent policy developments, including the cancellation of 31 renewable energy projects with a combined capacity of approximately 3,300 MW in September 2024, their reopening for review in April 2026, duty relief introduced in the FY2027 budget, and the rooftop solar incentive launched in September 2026.

Speaking on the institutional dimensions of Bangladesh’s energy transition, John Fluharty, Resident Programme Director at the International Republican Institute, emphasised the importance of transparency, accountability, and institutional trust.

He argued that a sustainable energy transition requires institutions capable of bringing different stakeholders into the decision-making process and ensuring clear oversight of public funds.

He stated, “The idea that transparency and accountability equals bureaucracy is just a bad way to look at it.”

He further emphasised that publishing information and establishing shared processes can strengthen trust and facilitate more effective decision-making.

Discussing the technical challenges facing Bangladesh’s electricity system, Mohammad Subail Bin Alam, COO of Rancon Infrastructures and Adjunct Faculty Member at the University of Liberal Arts Bangladesh, stated, “We are not ready.”

He explained that Bangladesh’s existing grid was primarily designed around a limited number of large power plants and one-way electricity flows. The expansion of rooftop and distributed solar, he noted, would require two-way distribution networks, upgraded transformers, advanced monitoring systems such as SCADA, and greater battery-storage capacity.

He further argued that transmission, generation, and monitoring infrastructure must be planned together if Bangladesh is to add the volume of renewable capacity required to meet its targets.

Referring to the experience of Pakistan, he noted that rapid solar expansion without adequate storage and grid planning could create additional pressure on the electricity system.

He also called for policy certainty of at least five years, greater coordination among institutions including SREDA and the Bangladesh Power Development Board, and increased access to concessional financing.

Highlighting the importance of transparency and reliable information, Md Ismail Ali, Editor of The Daily Jatiyo Arthoniti, called for the establishment of a centralised and publicly accessible digital energy database.

He suggested that such a system should be updated regularly and enable policymakers, investors, researchers, and citizens to compare renewable energy targets, installed capacity, and actual electricity generation.

He also raised concerns about short-term policy incentives, arguing that investors require greater certainty when making investments in infrastructure with long operational lifespans.

According to him, renewable energy projects cannot be effectively financed when policy commitments remain limited to short periods.

The moderator, Sakib Bin Amin, Senior Research Fellow at daira and Professor of Economics at North South University, highlighted the importance of addressing inefficiencies across Bangladesh’s wider electricity system.

He noted that transmission and distribution losses of nearly 10 per cent, compared with approximately 2–3 per cent globally, indicate significant scope for improving system efficiency.

Amin proposed greater use of public-private partnerships, including build-operate-transfer models, alongside the establishment of a national energy data centre and an environmental quality council.

He also emphasised the importance of strengthening energy storage capacity, monitoring subsidies to ensure they reach their intended beneficiaries, and promoting energy efficiency and demand-side management to reduce pressure on imported fuel.

The discussion also highlighted the importance of establishing a predictable policy environment for renewable energy investment.

Speakers emphasised that frequent changes in incentives, unclear institutional responsibilities, inadequate infrastructure, and limited access to affordable financing could undermine Bangladesh’s ability to translate renewable energy targets into actual projects.

Concluding the discussion, Sakib Bin Amin emphasised that Bangladesh’s challenge is increasingly one of implementation rather than target-setting.

He stated, “We need to connect policy with projects, projects with finance, finance with infrastructure, and generation with a grid capable of absorbing and delivering that electricity reliably.”

The webinar brought together representatives from academia, the private sector, media, research, and policy institutions to discuss the opportunities and challenges surrounding Bangladesh’s renewable energy transition.

The discussion formed part of daira’s broader engagement on sustainable development, economic policy, energy security, and emerging policy challenges in Bangladesh.​
 

442MW Rampal solar project awaits ECNEC approval


1791243271163.webp


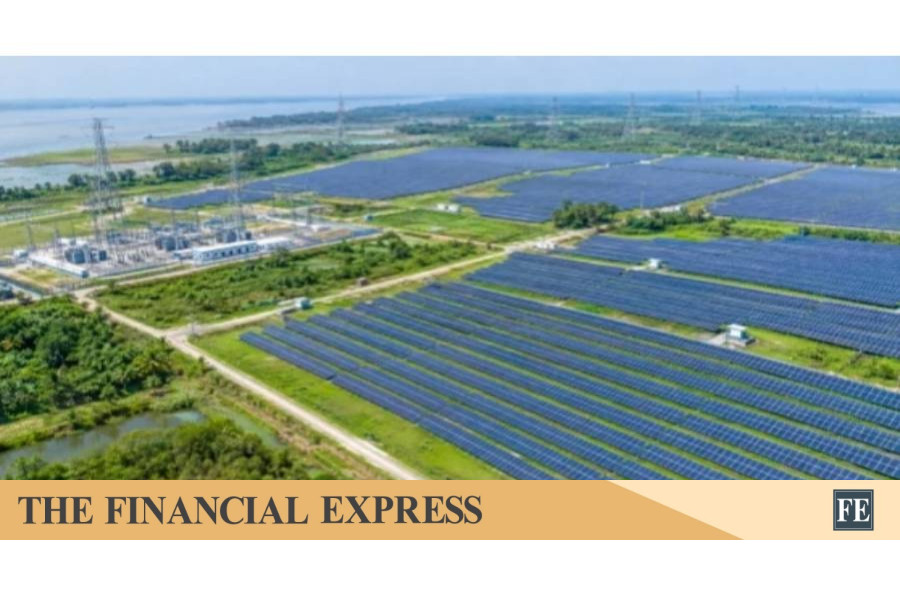
The government has planned to set up a Tk 2,502.39 crore project to build a 442-megawatt-peak (DC) solar photovoltaic power plant at Rampal in Bagerhat, aiming to increase renewable power generation and reduce dependence on fossil fuels.

The proposed “Construction of 442 MWp (DC) Solar Photovoltaic Grid-Connected Power Plant at Block-B, Rampal” project will be implemented by Bangladesh Power Development Board (BPDB) under the Power Division from July 2026 to December 2029, reports UNB.

The project proposal will be placed before the ECNEC on Wednesday for final approval, according to the Project Evaluation Committee (PEC) of the Planning Commission for scrutiny.

Of the total estimated cost, Tk 375.35 crore will come from BPDB’s own resources, while Tk 2,127.03 crore will be financed from the Power Sector Development Fund.

The Bangladesh Energy Regulatory Commission (BERC) had given in-principle approval on May 22, 2022, for financing Tk 2,380 crore, equivalent to 85 percent of the project’s then-estimated cost, from the Power Sector Development Fund.

The project will be implemented on 685 acres of usable land in Block-B of the Rampal power plant complex.

BPDB acquired 1,834 acres of land in Rampal in 2012, dividing it into Block-A, covering 915.50 acres, and Block-B, covering 918.50 acres.

Block-A houses the 1,320MW Maitree Super Thermal Power Plant, while Block-B remains under BPDB.

Land development, preservation work and construction of a boundary wall have already been completed there.

According to the project proposal, 76.63 acres of Block-B have been kept as a green belt, 32.87 acres for flood protection embankments, 94 acres as low-lying land and around 30 acres as a lake.

The proposed solar plant will include installation of solar panels, inverter stations, a pooling substation, power evacuation facilities and other civil works.

The project will also engage foreign consultants for 32 person-months and local consultants for 52 person-months.

Electricity generated by the plant will be converted to 230kV through 0.8/33kV and 33/230kV substations and evacuated through an approximately three-kilometre 230kV double-circuit transmission line to the adjacent Bangladesh-India Friendship Power Company Ltd (BIFPCL) 400/230kV substation.

Three new 230kV bays, including one spare, will have to be constructed at the BIFPCL substation for connecting the solar plant to the national grid.

The project proposal says the plant is intended to support the government’s renewable energy target, fuel diversification and reduction of carbon emissions.

It says Bangladesh’s power generation capacity currently stands at 32,332MW, with renewable sources accounting for 1,216MW, or 3.76 percent.

The government has set a target of raising the share of renewable energy in the overall energy mix to 20 percent by 2030, according to the proposal.

The project is also aligned with Sustainable Development Goal 7, which seeks affordable, reliable, sustainable and modern energy for all.

The proposal says the solar plant will help reduce reliance on gas, oil and coal and avoid emissions of carbon dioxide, sulphur oxides, nitrogen oxides and particulate matter associated with fossil-fuel-based generation.

The project was initially examined through an in-house feasibility study by BPDB in March 2022.

The Planning Commission has raised an issue over the feasibility study, noting that the relevant government guideline requires investment projects costing more than Tk 50 crore to undergo feasibility studies by experienced, independent and professional institutions or consultants.

However, a detailed feasibility study by Infrastructure Investment Facilitation Company (IIFC), a government-owned institution, was completed in May 2025.

Based on its recommendations, the draft Development Project Proposal (DPP) was sent to the Power Division on June 4, 2025.

The project scrutiny committee held a meeting on February 25, 2026, after which the Power Division sent the DPP to the Planning Commission.​
 

Bangladesh eyes LNG, fertiliser import from Algeria under G2G deal
Salahuddin further calls on Algeria to hire skilled workers from Bangladesh, including doctors and nurses


1791271964761.webp

Photo: UNB

Bangladesh and Algeria have set in motion a government-to-government (G2G) initiative for long-term imports of liquefied natural gas (LNG) and fertiliser.

Home Minister Salahuddin Ahmed disclosed the plan after a meeting with Algerian Ambassador to Bangladesh Dr Abdelouahab Saidani at his ministry office on Monday.


He said Bangladesh will import LNG and fertiliser from Algeria under the G2G framework.

Salahuddin also urged Algeria to widen the trade basket in Dhaka's favour, saying Algiers could increase imports of Bangladeshi garments and pharmaceutical products.

Salahuddin further called on Algeria to hire skilled workers from Bangladesh, including doctors and nurses.

Beyond trade and energy, the two sides discussed maintaining peace and order, security cooperation, preventing and combating human trafficking, migration management, and expanding economic and commercial ties.

They laid particular emphasis on specialised training to improve the efficiency and professionalism of security forces, joint workshops, and the exchange of legislative support.

Recalling that Algeria was the first Arab country to recognise Bangladesh after its independence in 1971, the ambassador voiced his country's strong interest in further strengthening the historic and friendly relationship.

Referring to the invitation extended by Prime Minister Tarique Rahman to the Algerian President to visit Dhaka, Salahuddin said Bangladesh is pleased that the invitation has been accepted.

He stressed fixing a mutually convenient diplomatic date for the visit.

At the end of the meeting, both countries reaffirmed their commitment to deepening and strengthening cooperation in security, trade and bilateral diplomatic relations.​
 

Bringing volatile LPG market to order


1791328959328.webp


The Bangladesh Energy Regulatory Commission (BERC)'s decision on Sunday to raise the price of a 12-kg cylinder of liquefied petroleum gas (LPG) by Tk252 to Tk1,837 at one go is a jolt to common consumers. The regulator reportedly attributed the increase to higher international prices of propane and butane (constituents of LPG), enhanced freight and traders' premiums and increased transportation costs following the equally cut-throat fuel-oil price hike. The BERC expects the adjustment would bring the volatile LPG market to order. But will a higher official price stabilise a market when the prices fixed earlier by the regulator were hardly ever complied with? In September, when BERC fixed LPG price, in many places consumers had to pay up to Tk500 more for a cylinder of the gas. After the latest hike of LPG price, dealers are charging an additional amount between Tk 300 and Tk 400 for a 12-kg cylinder. Clearly, the problem is not purely one of price-setting.

Intriguingly, the price instability persists despite LPG operators' claim that there is no overall shortage. According to the LPG Operators Association of Bangladesh (LOAB), the quantities of LPG imported in the previous two months should be enough to meet domestic demand. The government also reviewed National Board of Revenue (NBR) data on import, stock and supply and found the overall position satisfactory. Furthermore, it has, facilitated private operators by restructuring the tax regime, removing VAT at production and trading stages and advance tax on imports while raising import and storage limits. The government-imported LPG is also in the market to supplement private supply. Yet the benefits provided to businesses are not being reflected at the consumers' end. For households without pipeline gas, LPG is not a luxury but an essential cooking fuel. So, to claim that LPG imports are adequate is cold comfort for the consumer public as they have to pay through the nose for a cylinder.

Against this backdrop, the BERC's instruction to a number of LPG importers for submission of their September sales information deserves attention. The regulator reportedly sought details of sales to bottled-gas consumers, industries and autogas users following allegations that supplies to the retail market were deliberately squeezed in anticipation of a price increase. Distributors, on the other hand, complain that they are not getting LPG from operators at regulator-approved rates, while importers reject the allegation. Somewhere between import terminal, storage, bottling plant, distributor, dealer and retailer, the officially determined price is being lost. That should not remain a matter of allegation and counter-allegation. If imports are sufficient, there has to be an explanation why cylinders disappear from shops and reappear at prices far above the BERC rate. The repeated failure to enforce the official price also raises a basic question about the usefulness of monthly price announcements unless the regulator can ensure compliance throughout the supply chain.

In that case, the government and BERC need to move beyond issuing warnings and conducting sporadic market drives. What is necessary is a real-time system of keeping tabs on how much LPG each operator imports, stores, bottles and sells, to whom and at what stage of the distribution chain. Those data should be matched with customs records and periodically audited so any unexplained withholding of supply can be detected early. Genuine increases in international price and freight costs have to be reflected in domestic prices. True, no market can be insulated from global realities. But such cost increases cannot be an excuse for artificial scarcity or profiteering. The government, therefore, should track down the rackets behind artificial supply crisis of LPG before meting out punishment to those responsible.​
 

Unlocking the potential of wind power


1791329054514.webp


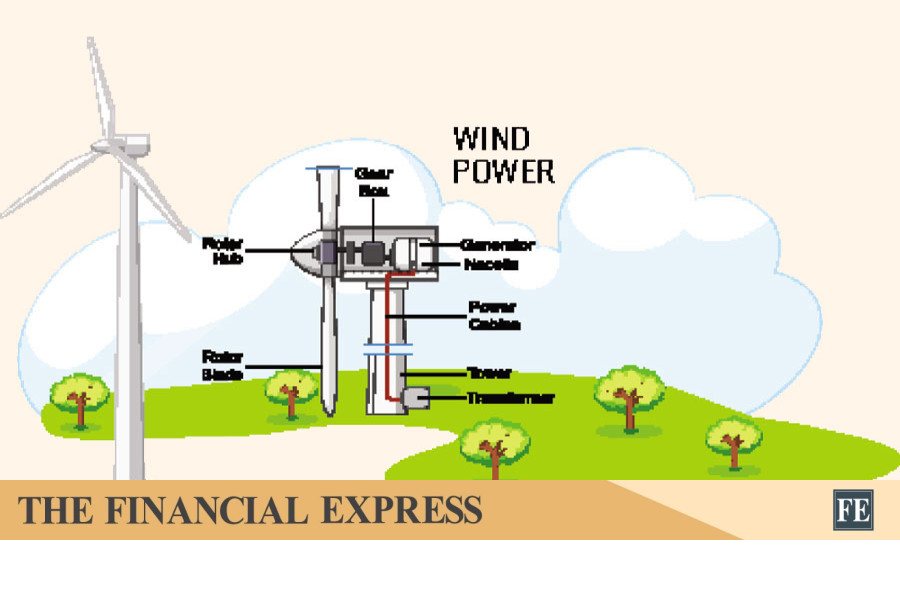
As energy security rises ever higher on the government's agenda, exploring every viable source of energy has become an imperative. Leaving any potential energy source unexplored is no longer an option. Against this backdrop, the government's decision to introduce comprehensive guidelines for developing onshore wind-power projects marks a timely and potentially transformative step towards diversifying the country's energy mix.

The newly unveiled framework seeks to establish a clear and transparent pathway for the development of land-based wind power projects. Industry leaders have welcomed the initiative, expressing optimism that the guidelines will encourage greater private-sector participation while enabling Bangladesh to unlock what many believe to be its still largely untapped wind-energy potential. More importantly, the framework reflects growing policy recognition that achieving long-term energy security will require the country to move decisively beyond its overwhelming reliance on conventional fuels.

Wind energy has long been regarded as one of the world's most promising renewable resources. It is clean, inexhaustible and increasingly cost-competitive as technological advancements continue to improve turbine efficiency and reduce generation costs. Unlike fossil-fuel-based power plants, wind farms emit no greenhouse gases during operation and require no imported fuel. For a country like Bangladesh, which spends billions of dollars annually on importing coal, liquefied natural gas and petroleum products, the economic significance of such a resource extends well beyond environmental considerations. Every additional megawatt generated from domestic renewable sources lessens the country's vulnerability to international fuel-market shocks and contributes to greater energy independence.

According to the Sustainable and Renewable Energy Development Authority (SREDA), Bangladesh possesses modest but commercially viable onshore wind resources. These are concentrated primarily along the country's 710-kilometre coastline, the Chittagong Hill Tracts and selected open plains in the north-west. Extensive wind-resource mapping conducted jointly by SREDA and international partners has identified several promising sites where average annual wind speeds range between 5.0 and 7.5 metres per second at hub height-sufficient for utility-scale electricity generation using modern wind-turbine technology.

Yet despite this encouraging resource assessment, Bangladesh has barely begun to harness wind energy. At present, the country generates only 62 megawatts of electricity from wind out of a total renewable-energy capacity of 1,807 megawatts. The figure is strikingly small when viewed against the government's ambitious targets under the Renewable Energy Policy 2025, which aims to generate 20 per cent of the country's electricity from renewable sources by 2030 and 30 per cent by 2040.

The newly adopted guideline therefore deserves attention not merely as another regulatory document but as an effort to remove many of the uncertainties that have historically discouraged investment in renewable energy projects. Investors are often reluctant to commit capital where regulatory procedures remain ambiguous or project risks are difficult to assess. By laying down technically robust minimum standards aligned with internationally recognised benchmarks such as IEC 61400-1, IEC 61400-12 and the IFC Performance Standards, the government aims to provide developers, financiers and lenders with greater confidence that projects can be implemented under predictable rules.

Renewable-energy projects typically require substantial upfront investments and depend heavily on long-term financing. Financial institutions are far more willing to support projects where regulatory requirements, land acquisition procedures, environmental compliance and grid-access arrangements are clearly defined. In this respect, the guideline attempts to reduce uncertainty by establishing a transparent regulatory pathway from project conception to commissioning.

The provisions relating to land acquisition and project implementation are particularly significant. Developers are required to ensure that all lands needed for turbines, substations, access roads, meteorological masts, cable routes and related infrastructure are legally available and comply with existing land-use regulations and environmental restrictions. Where the government allocates land for wind development, developers will have three years to complete project development and begin commissioning, although extensions may be granted in justified circumstances. Such provisions seek to strike a balance between preventing speculative land occupation and allowing sufficient flexibility for genuine investors facing unforeseen delays.

Another notable feature is the requirement to verify technical and commercial feasibility of grid connectivity before making investment commitments. This addresses one of the persistent challenges confronting renewable-energy projects worldwide. Electricity generation alone cannot ensure project success unless adequate transmission infrastructure exists to evacuate power efficiently.

The guideline also rightly encourages the integration of energy-storage systems alongside wind farms. As renewable-energy penetration increases, maintaining grid stability becomes increasingly important because wind generation naturally fluctuates with weather conditions. Battery storage technologies can smooth these variations, improve electricity dispatch, reduce curtailment and enhance overall grid reliability. Such integrated systems are rapidly becoming an essential component of modern renewable energy development across the world.

However, regulatory reform alone will not guarantee success. Wind-power development will ultimately depend on policy consistency, competitive financing, efficient approval processes and continued investment in transmission infrastructure. The government must also strengthen institutional capacity, ensure timely project implementation and maintain investor confidence through transparent decision-making. At the same time, local communities should be meaningfully engaged throughout project development to minimise social conflicts and ensure that environmental safeguards are rigorously observed.

The road ahead will undoubtedly present challenges. But every successful energy transition begins with the creation of credible institutions and sound policies. The new onshore wind-power guideline is one such building block. If implemented with sincerity, consistency and long-term vision, it can help transform Bangladesh's abundant coastal winds from an overlooked natural phenomenon into a dependable source of clean electricity and environmental stewardship.​
 

Latest Posts

Back